 ultimate-guide
Safe Withdrawal Rates for Retirement: 2026 Guide
Table of Contents
- Understanding Safe Withdrawal Rates
- The 4% Rule Explained
- Sequence of Returns Risk and Market Timing
- Retirement Withdrawal Strategies Beyond the 4% Rule
- Tax-Efficient Withdrawal Order for Long-Term Savings
- Using Portfolio Longevity Calculators to Test Your Plan
- Adjusting Your Withdrawal Rate for Inflation and Life Changes
- Conclusion
- Frequently Asked Questions
Last Updated: August 11, 2026
Understanding Safe Withdrawal Rates
Safe withdrawal rates represent the percentage of your retirement portfolio you can withdraw annually while maintaining a high probability that your money lasts throughout your retirement. This concept sits at the heart of retirement income planning because it bridges the gap between what you've saved and what you can actually spend.
The challenge is real: you've accumulated wealth over decades and now need to convert that nest egg into reliable income without depleting it prematurely. Withdraw too much and you risk running out of money; withdraw too little and you forgo years of enjoyment during your healthiest retirement years.
At New Insight Financial, we help individuals and couples navigate this tension. The traditional 4% rule provides a starting point, but your personal safe withdrawal rate depends on far more than a single percentage. Your portfolio composition, market timing, tax situation, and life expectancy all influence how much you can safely withdraw.
This guide moves beyond simple rules of thumb to show you how to think strategically about withdrawal rates. You'll learn why sequence of returns risk matters, how to structure tax-efficient withdrawals, and how to adjust your strategy as circumstances change.
The 4% Rule Explained
The 4% rule emerged from research suggesting that retirees could withdraw 4% of their initial portfolio in year one, then adjust that dollar amount for inflation in subsequent years, with a high success rate over a 30-year retirement.
Here's how it works: If you retire with a $1 million portfolio, you'd withdraw $40,000 in year one. In year two, if inflation was 2%, you'd withdraw $40,800, and so on. The rule assumes a balanced portfolio of 60% stocks and 40% bonds based on historical average market returns.
The appeal is obvious: you get a concrete number and can calculate your required portfolio size based on spending needs. A retiree needing $60,000 annually would target roughly $1.5 million in savings.
However, the 4% rule is based on historical averages, not future guarantees. Market returns vary dramatically year to year, and the sequence in which returns occur, whether you face a market crash in year one versus year ten, dramatically affects portfolio longevity. A bad market at the wrong time can derail even a mathematically sound plan.
Sequence of Returns Risk and Market Timing
Sequence of returns risk is the possibility that investment returns will arrive in an unfavorable order, depleting your portfolio faster than expected based on average returns alone.
Consider two scenarios with identical 7% average annual returns over 10 years. In Scenario A, you experience strong returns early (12%, 11%, 10%) and weaker returns later (3%, 2%, 1%). In Scenario B, the order reverses. If you're withdrawing money, Scenario B poses far greater threat to your portfolio. You're forced to sell more shares when prices are low to fund withdrawals, locking in losses and reducing shares available to benefit from later recovery.
This risk is especially acute in the first five to ten years of retirement, the "sequence of returns risk window." A market downturn early in retirement can be devastating because you lack time to recover through continued employment income.
Strategic responses include maintaining a spending floor (minimum withdrawal regardless of market performance) and a spending ceiling (reduced during downturns). Some retirees keep one to two years of spending needs in cash or bonds, allowing them to avoid selling stocks during market crashes.
Retirement Withdrawal Strategies Beyond the 4% Rule
Fixed percentage withdrawals have given way to more sophisticated strategies that acknowledge retirement isn't static and rigid rules often fail when circumstances change.
The guardrails approach sets upper and lower spending boundaries. You establish a target withdrawal rate, but increase spending if your portfolio grows beyond a threshold and reduce it if it shrinks below another. This maintains flexibility while preventing catastrophic overspending or unnecessary deprivation.
The floor-and-upside strategy separates guaranteed income needs from discretionary spending. Essential expenses are covered by Social Security, pensions, or bond income, while everything above becomes discretionary spending funded by equity returns. This psychological separation reduces anxiety during market downturns because essential needs remain protected.
The bucket strategy divides your portfolio into time-based buckets: Bucket One holds one to two years of spending in cash and short-term bonds; Bucket Two holds three to ten years of needs in intermediate-term bonds and balanced investments; Bucket Three holds longer-term money in growth-oriented equities. During market downturns, you spend from Bucket One while stocks recover, reducing pressure to sell equities at the worst time.
The dynamic spending approach adjusts withdrawals annually based on portfolio performance and market conditions. In strong market years, you increase spending; in weak years, you reduce it. While this requires discipline and flexibility, it significantly improves portfolio longevity.
Each strategy has trade-offs. Fixed-percentage approaches are simple but inflexible. Dynamic approaches preserve portfolio longevity but require ongoing attention. The right choice depends on your personality, portfolio size, and spending flexibility.
Tax-Efficient Withdrawal Order for Long-Term Savings
Where you withdraw from matters as much as how much you withdraw. The order of withdrawals can reduce your lifetime tax bill by tens of thousands of dollars.
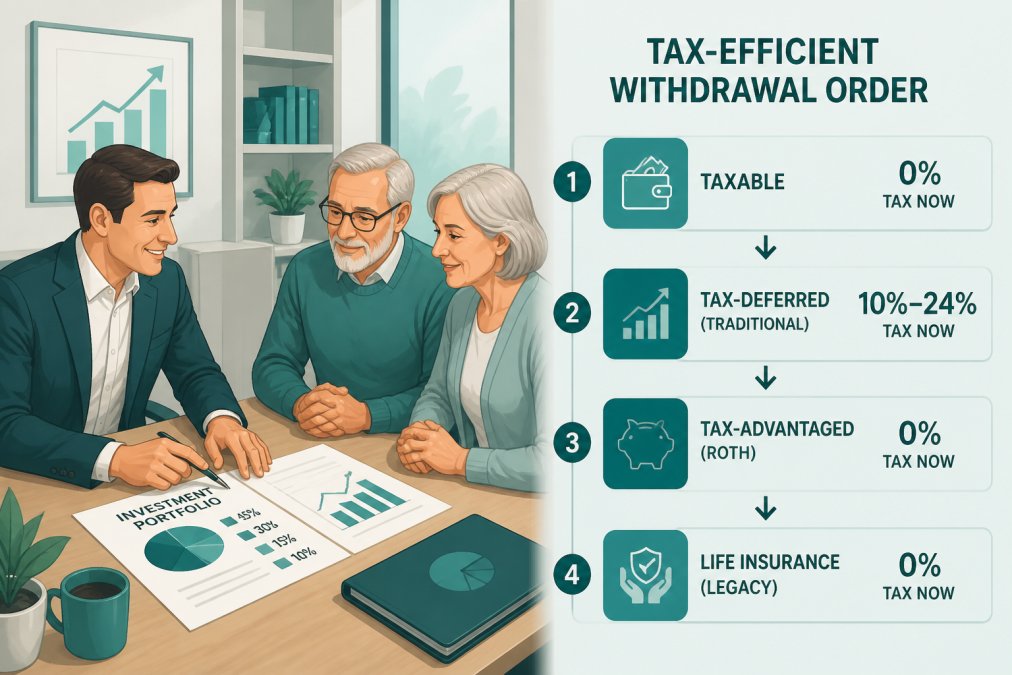
The general principle is to withdraw from taxable accounts first, then tax-deferred accounts like traditional IRAs, and finally tax-free accounts like Roth IRAs. This allows tax-free and tax-deferred accounts to continue growing through compound returns while you fund current spending from taxable sources.
However, this rule has important exceptions. If you're in a low tax bracket early in retirement, before claiming Social Security or before Required Minimum Distributions begin at age 73, it may make sense to convert traditional IRA funds to a Roth IRA while in that low bracket. You'll pay taxes at favorable rates, and the money grows tax-free forever.
If you hold appreciated securities in taxable accounts, consider which specific shares you sell. Tax-loss harvesting, selling losing positions to offset gains elsewhere, minimizes your annual tax bill. Holding appreciated securities until death allows heirs to receive a "step-up in basis," avoiding capital gains taxes on your appreciation.
Many retirees overlook the interaction between withdrawal strategy and Social Security taxation. Up to 85% of Social Security benefits can be taxable if your combined income exceeds certain thresholds. Strategic withdrawals from tax-deferred accounts can reduce this taxation by keeping combined income lower.
Required Minimum Distributions begin at age 73 and force you to withdraw a percentage of tax-deferred accounts annually at ordinary income rates. Planning ahead, perhaps by converting portions of your traditional IRA to a Roth before RMDs begin, can reduce the tax impact.
Using Portfolio Longevity Calculators to Test Your Plan
Portfolio longevity calculators help you stress-test your withdrawal strategy against historical market scenarios. Rather than relying on average returns, these tools run thousands of simulations using actual historical return sequences to determine the probability that your portfolio will survive your planned withdrawal rate.
A Monte Carlo simulation generates random market scenarios based on historical volatility patterns. If your plan succeeds in 95% of simulated scenarios, you have a 95% success probability. If it fails in 30% of scenarios, your plan has only a 70% success rate, probably too risky for most retirees.
These calculators typically ask for your starting portfolio balance, annual spending needs, asset allocation, and planned retirement duration. The value lies not in false precision but in perspective. Running your numbers through multiple scenarios helps you understand the risks you're taking and whether to adjust spending, work longer, or accept greater risk.
Adjusting Your Withdrawal Rate for Inflation and Life Changes
Inflation erodes purchasing power. A withdrawal rate that works today may leave you struggling in ten years if inflation accelerates. Most retirement plans assume a long-term inflation rate around 2-3% annually.
The cost-of-living adjustment, or COLA, is the mechanism most retirees use to address inflation. You increase withdrawals each year by the inflation rate, maintaining constant purchasing power. If you withdrew $40,000 in year one and inflation was 3%, you'd withdraw $41,200 in year two.
However, inflation isn't uniform across all spending categories. Healthcare costs typically inflate faster than general inflation. If you're spending heavily on healthcare in retirement, you may need to increase that category's withdrawals faster than your overall inflation adjustment.
Life changes also require withdrawal rate adjustments. A health diagnosis might increase medical spending. A spouse's death changes household expenses and potentially Social Security income. Moving to a lower cost-of-living area might allow you to reduce withdrawals. Dynamic spending strategies address this reality by building in annual adjustments based on actual portfolio performance and life circumstances.
Conclusion
Safe withdrawal rates form the foundation of a successful retirement income strategy. While the 4% rule provides a useful starting point, your personal safe withdrawal rate depends on your specific circumstances, risk tolerance, and flexibility. Sequence of returns risk, tax efficiency, portfolio composition, and life changes all influence how much you can safely withdraw.
The most successful retirees don't pick a withdrawal rate and forget it. They build flexibility into their plans, monitor portfolios regularly, and adjust when circumstances warrant. Retirement planning isn't a one-time calculation; it's an ongoing process of refinement and adaptation.
At New Insight Financial, we help retirees move beyond generic rules to develop withdrawal strategies tailored to their unique situations. Our approach considers your entire financial picture, income sources, tax situation, health outlook, and family goals. We use portfolio longevity calculators to stress-test your plan, help you structure tax-efficient withdrawals, and provide ongoing guidance that helps you adjust as life unfolds. Your retirement years should be about enjoying the life you've built, not worrying about whether your money will last. Get Started Today with a consultation to review your retirement income plan.
| Strategy | Best For | Key Benefit | Primary Consideration |
|---|---|---|---|
| 4% Rule | Simplicity-focused retirees | Easy to understand and implement | May not adapt to market changes |
| Guardrails Approach | Flexible spenders | Balances consistency with adjustment | Requires monitoring |
| Floor-and-Upside | Security-focused retirees | Protects essential spending | Requires income diversification |
| Bucket Strategy | Risk-averse retirees | Reduces forced selling in downturns | More complex to manage |
| Dynamic Spending | Active managers | Maximizes portfolio longevity | Requires discipline and flexibility |
Frequently Asked Questions
Is the 4% rule still a safe withdrawal rate in 2026?
The 4% rule remains a foundational benchmark for safe withdrawal rates, but its effectiveness depends on your specific circumstances. Market conditions, portfolio composition, inflation, and your retirement timeline all influence whether 4% is appropriate for your situation. Some retirees may sustain higher rates with strong asset allocation and dynamic spending adjustments, while others may need to be more conservative. Working with a financial advisor to stress-test your withdrawal rate against various market scenarios helps determine if 4% aligns with your retirement goals and risk tolerance.
How does sequence of returns risk affect my safe withdrawal rate?
Sequence of returns risk occurs when poor market returns early in retirement can significantly reduce your portfolio's longevity, even if long-term average returns are strong. A major market downturn in your first five years of withdrawals can deplete your capital faster than expected, making it harder to recover. This risk is why many retirees benefit from maintaining a spending floor (essential expenses) covered by stable income sources like Social Security and pensions, while using portfolio withdrawals for discretionary spending. Dynamic withdrawal strategies that reduce spending during down markets help protect against this sequence risk.
What is tax-efficient withdrawal order and why does it matter?
Tax-efficient withdrawal order means drawing from your accounts in a specific sequence to minimize lifetime tax liability. Generally, you withdraw from taxable accounts first, then tax-deferred accounts like traditional IRAs, and finally tax-free accounts like Roth IRAs. This approach lets tax-deferred and tax-free accounts grow longer while you manage taxable gains strategically. The order matters because taxes can significantly reduce your portfolio's longevity over 30+ years of retirement. Consider consulting a tax professional to optimize your withdrawal sequence based on your specific account types, income needs, and tax brackets.
How can portfolio longevity calculators help me plan my retirement withdrawals?
Portfolio longevity calculators use historical market data and Monte Carlo simulations to estimate the probability that your savings will last through your retirement. They let you test different withdrawal rates, asset allocations, and spending scenarios to see how your portfolio performs across various economic conditions. By running these projections, you can identify whether your planned withdrawal rate has a high success probability (typically 90-95%) or if you need to adjust your spending, delay retirement, or modify your asset allocation. These tools provide concrete evidence to support your withdrawal strategy rather than relying on general rules alone.