 ultimate-guide
Retirement Income Planning for Couples: A Complete Guide
Table of Contents
- Why Retirement Income Planning for Couples Differs From Solo Planning
- Establishing Shared Retirement Vision and Financial Goals
- Budgeting for Post-Retirement Household Expenses
- Social Security Spousal Benefits Strategy for Married Couples
- Retirement Tax Planning for Married Couples
- How to Synchronize Retirement Dates and Income Coordination
- Best Retirement Withdrawal Strategies for Couples
- Healthcare, Long-Term Care, and Estate Planning for Couples
- Frequently Asked Questions
Retirement Income Planning for Couples: A Complete Guide
Last Updated: July 13, 2026
Retirement income planning for couples requires coordinating income streams, Social Security decisions, and shared assets in ways that single retirees never face. The difference between a well-coordinated plan and an ad-hoc approach often amounts to tens of thousands of dollars over a 30-year retirement.
This guide covers essential strategies for couples: establishing shared goals, coordinating tax-efficient withdrawals, optimizing Social Security, and planning for healthcare. You'll learn how to maximize household income and avoid costly mistakes.
Why Retirement Income Planning for Couples Differs From Solo Planning
Solo retirement planning focuses on one person's needs and lifespan. Couples face dual Social Security claiming strategies, spousal benefits, survivor benefits, coordinated withdrawals, and the possibility that one spouse outlives the other by 15+ years.
The math changes dramatically. When one spouse claims Social Security early and the other delays, household income shifts. When assets are held in different account types, withdrawal sequencing affects your long-term tax bracket. Couples have more levers to pull than individuals, spousal benefits, survivor benefits, pension options, and coordinated withdrawal strategies can collectively add years of financial security.
Establishing Shared Retirement Vision and Financial Goals
Before spreadsheet work, couples need clarity on what retirement means to them. Retirement vision goes beyond numbers, it's about lifestyle, location, travel frequency, healthcare preferences, and what success looks like for both partners.
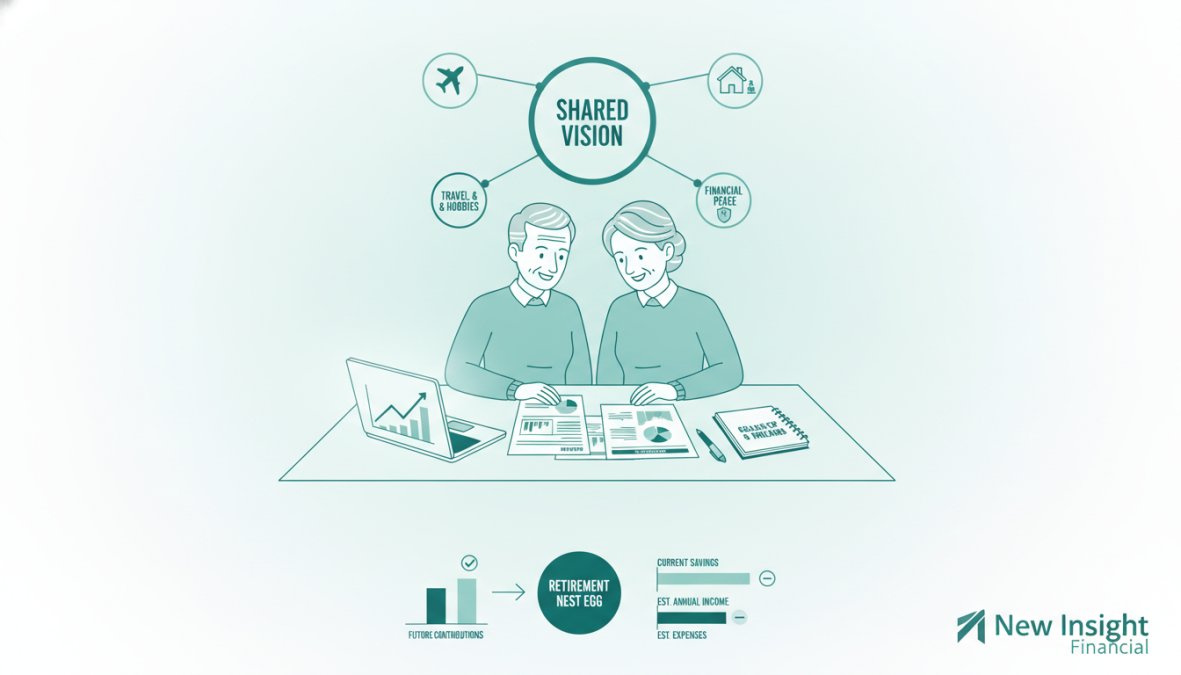
Many couples discover they have different retirement timelines. One partner imagines retiring at 62, the other at 70. One wants to travel extensively; the other prefers staying close to family. These differences are starting points for negotiation, not obstacles.
Addressing Non-Financial Emotional Alignment
The financial plan only works if both partners feel heard and valued. Couples often have different relationships with money shaped by family history and life experience. One partner may prioritize security; the other prioritizes freedom and experiences.
Effective planning requires surfacing these emotional drivers explicitly. Ask each other: What does financial security mean to you? What would make you feel retirement is failing? Once you understand each other's emotional landscape, you can design a plan addressing both math and psychology.
Handling Unequal Income and Savings Gaps
Many couples arrive at retirement with vastly different savings levels. One partner may have earned significantly more or taken time out for caregiving. Reframe retirement income as household income, both partners contributed through paid work, caregiving, and managing finances. Both have earned the right to retire.
Budgeting for Post-Retirement Household Expenses
Retirement budgeting differs from pre-retirement budgeting because expense structures change. Mortgage payments may disappear; commuting costs vanish. But healthcare costs rise, and leisure activities may cost more than expected.
Categorize retirement expenses into three buckets: essential (housing, food, utilities, insurance), discretionary (travel, hobbies, dining out), and legacy (gifts, charitable giving, inheritance). Estimate realistic annual costs for each.
Essential expenses usually remain stable. Discretionary expenses often spike in the first 5-10 years of retirement, then decline as mobility decreases. Healthcare is the wildcard, many couples underestimate costs. Long-term care can cost $50,000-$100,000 per year and isn't covered by Medicare.
Social Security Spousal Benefits Strategy for Married Couples
Social Security is often the largest single source of retirement income for couples, representing 30-40% of total retirement income. The claiming strategy, who claims when, can shift household income by tens of thousands of dollars over a lifetime.
Couples have access to benefits singles don't: spousal benefits and survivor benefits. A lower-earning spouse can claim up to 50% of the higher-earning spouse's full retirement age benefit, even with no earnings record. This was designed to protect spouses who took time out for caregiving.
The optimal claiming strategy depends on age gap, life expectancy, income gap, and pensions. If both spouses have similar earnings, a common strategy is for the lower-earning spouse to claim at full retirement age (66-67) while the higher-earning spouse delays until 70. This maximizes lifetime benefits because the higher earner's benefit grows 8% annually from full retirement age to 70. Research shows coordinated claiming strategies can increase lifetime household benefits by $50,000-$200,000 compared to claiming at the earliest opportunity.
Claiming Age and Survivor Benefits Coordination
Survivor benefits add another layer to Social Security strategy. If one spouse dies, the surviving spouse receives a benefit based on the deceased's earnings record. The survivor benefit equals what the deceased was receiving (or entitled to receive).
This means the claiming decision affects household income during both spouses' lifetimes and the surviving spouse's income after one partner's death. A spouse who claims at 62 receives a reduced benefit; the survivor benefit is also reduced. A spouse who delays until 70 receives a higher benefit, and the survivor benefit is correspondingly higher.
For couples where one spouse is significantly older or in poor health, survivor benefits may be the primary consideration. For many couples, consulting a financial advisor who specializes in Social Security optimization is worth the cost. The difference between suboptimal and optimized strategies can exceed $100,000 in lifetime household benefits.
Retirement Tax Planning for Married Couples
Taxes consume a significant portion of retirement income for many couples. The difference between tax-aware and tax-blind planning can amount to 10-15% of total retirement spending power over 30 years.
Tax planning for couples is more complex than for individuals because you're managing two income streams, two Social Security benefits, two sets of retirement accounts, and their interactions. A withdrawal from your spouse's traditional IRA affects your combined taxable income, which affects Medicare premiums, Social Security taxation, and your tax bracket.
Tax-Efficient Withdrawals and Tax Bracket Management
Tax-efficient withdrawal sequencing means pulling money from various accounts strategically to minimize lifetime taxes. The general principle is to exhaust tax-deferred accounts (traditional 401(k)s and IRAs) before touching tax-free accounts (Roth IRAs), while managing your tax bracket to avoid unnecessary Social Security taxation and Medicare premium surcharges.
For couples, this is a household decision. A common approach is taking early retirement income from taxable accounts (brokerage accounts) to keep adjusted gross income low. This preserves your ability to do Roth conversions at favorable rates and keeps Social Security taxation low. Once Social Security begins, you may shift to withdrawing from traditional retirement accounts.
When one spouse has a pension and the other doesn't, tax planning becomes asymmetrical. The pension provides fixed income you can't control. Your withdrawal strategy must account for this and coordinate around it.
State-Specific Tax Considerations
State income taxes dramatically affect retirement income. A couple earning $100,000 faces different tax bills in Florida (no state income tax), California (13.3% top rate), or New York (6.85% top rate).
Some states exempt Social Security from taxation or offer pension income exclusions. If you have flexibility in where to live, your state of residence meaningfully affects retirement income. For couples with substantial retirement income, state tax planning may involve relocating to a more tax-efficient state.
How to Synchronize Retirement Dates and Income Coordination
One spouse often wants to retire before the other. This creates a transition period where one partner is retired while the other works. Managing this requires thought about household income, Social Security timing, and investment strategy.
If the early-retiring spouse is significantly older, their Social Security will likely begin first. This creates staggered income. Early in retirement, household income may come primarily from the working spouse's salary and the retired spouse's Social Security.
The working spouse's continued income affects the early-retired spouse's Social Security. If the early-retired spouse claims before full retirement age and household income exceeds the Social Security earnings limit, their benefit is reduced by $1 for every $2 earned above the limit.
Managing Retirement Age Gaps Between Spouses
A significant age gap (8-10 years) creates unique challenges. The older spouse may retire at 62-65 while the younger continues working until 70. This creates a long transition period with asymmetrical household income.
A large retirement age gap means one spouse will likely spend many years in retirement alone. If the older spouse dies first, the younger may have 20-30 years of single retirement ahead. This makes survivor benefits and life insurance important considerations.
Best Retirement Withdrawal Strategies for Couples
The 4% rule, withdrawing 4% of your portfolio in year one, then adjusting for inflation, is a common starting point. But for couples, this needs nuance.
401(k) and IRA Coordination Across Accounts
Most couples have retirement savings spread across multiple account types: one spouse's 401(k), the other's IRA, a joint brokerage account, maybe a Roth IRA. Coordinating withdrawals across these accounts is essential for tax efficiency.
The general principle is withdrawing from accounts in an order that minimizes taxes. Taxable accounts (brokerage) usually come first, since withdrawals don't affect adjusted gross income. Traditional retirement accounts come next, as withdrawals are taxable but you control timing. Roth accounts come last, since withdrawals are tax-free.
This sequencing must account for required minimum distributions (RMDs). Starting at age 73, you must withdraw a minimum from traditional retirement accounts. A coordinated withdrawal strategy maps out year by year which accounts to tap to keep household income in an efficient tax bracket while meeting spending needs and satisfying RMD requirements.
Safe Withdrawal Rates and Income Replacement Ratios
If one spouse is significantly older, the younger spouse may have 40+ years of retirement ahead. A 4% rate may not be sustainable; 3-3.5% may be more appropriate.
If you have a pension or substantial Social Security income, you may withdraw more than 4% from your portfolio, since it doesn't need to sustain your entire lifestyle.
Healthcare, Long-Term Care, and Estate Planning for Couples
Healthcare costs represent one of the largest and most unpredictable retirement expenses. A couple retiring at 65 can expect to spend $315,000+ on healthcare throughout retirement, including Medicare premiums, deductibles, copays, and out-of-pocket costs for services Medicare doesn't cover.
For couples, healthcare planning involves coordinating two people's needs, two sets of Medicare decisions, and potentially different health trajectories.
Medicare Enrollment and Long-Term Care Insurance
Medicare enrollment is more complex for couples. You and your spouse may have different retirement dates, different health insurance situations, and different enrollment timelines. Missing a Medicare deadline results in permanent late-enrollment penalties.
Long-term care insurance is critical. Long-term care, nursing home, assisted living, or in-home care, costs $50,000-$100,000+ annually and isn't covered by Medicare. For couples, the risk is that one spouse needs extensive care while the other is healthy and independent. If one spouse requires five years of nursing home care at $75,000 annually, that's $375,000 in unexpected expenses that can devastate a plan that didn't account for it.
Beneficiary Designations and Estate Planning
Beneficiary designations on retirement accounts and life insurance override your will and determine who receives the account if you die. If you designate your ex-spouse and later remarry, your ex may still receive your retirement accounts unless you update the designation.
For couples, keeping beneficiary designations current is essential. After marriage, update all retirement accounts to name your spouse as primary beneficiary. Name contingent beneficiaries (typically children or a trust) to receive the account if your spouse predeceases you.
For IRAs, naming a spouse as beneficiary has significant tax advantages. A surviving spouse can roll over an inherited IRA into their own and defer distributions. A non-spouse beneficiary must begin taking distributions immediately, accelerating taxation.
Retirement income planning for couples is complex, but the effort pays dividends. A coordinated strategy aligning both partners' goals, optimizing Social Security, coordinating tax-efficient withdrawals, and planning for healthcare can add meaningful security and flexibility to retirement.
New Insight Financial specializes in helping couples develop personalized retirement strategies. Our team can help you coordinate Social Security claiming decisions, design tax-efficient withdrawal strategies, and plan for healthcare costs and long-term care. We also provide secure access to the Generational Vault® for organizing essential financial and legal documents. Get started with New Insight Financial today and build a retirement plan designed for both of you.
| Strategy | Primary Benefit | Best For | Key Consideration |
|---|---|---|---|
| Delayed Social Security (one spouse to 70) | Maximizes lifetime household benefits | Higher-earning spouse with longer life expectancy | Requires other income source early in retirement |
| Staggered retirement dates | Allows gradual transition and income adjustment | Couples with age gap or different work preferences | Requires coordination of healthcare and withdrawals |
| Tax-loss harvesting coordination | Reduces capital gains taxes across household | Couples with significant investment accounts | Requires active management and monitoring |
| Long-term care insurance | Protects assets from catastrophic care costs | Couples with substantial assets to protect | Premiums increase with age; underwriting required |
| Roth conversion strategy | Creates tax-free income in later retirement | Couples in lower tax brackets early in retirement | Requires sufficient cash flow to pay taxes |
Frequently Asked Questions
How do couples coordinate retirement income planning effectively?
Couples should start by aligning on shared retirement vision and goals, then coordinate across accounts and income sources. This includes synchronizing Social Security claiming strategies, establishing a joint retirement budget, and planning tax-efficient withdrawals from 401(k) and IRA accounts. Regular financial advisor consultations ensure both spouses understand the plan and can adjust for life changes like retirement age gaps or income shifts.
What is the best Social Security spousal benefits strategy for married couples?
The optimal strategy depends on claiming age, life expectancy, and income levels. Higher-earning spouses often claim later to maximize survivor benefits, while lower-earning spouses may claim earlier. Couples should evaluate how spousal benefits and survivor benefits interact with their overall retirement income plan. A financial advisor can model different claiming scenarios to identify the strategy that maximizes household lifetime benefits.
How should couples handle unequal income and savings in retirement planning?
Couples with unequal savings should clarify ownership and access to accounts early. Consider whether to pool resources or maintain separate accounts based on your situation. Retirement tax planning for married couples can leverage the lower-earning spouse's tax bracket for strategic withdrawals. Discuss how survivor benefits and spousal protections work if one spouse has significantly less retirement savings, and consult a financial advisor to structure accounts fairly.
What happens to retirement income planning if spouses have different retirement dates?
When spouses retire at different times, coordinate your withdrawal strategy to manage household cash flow. The working spouse may continue contributing to 401(k) and IRA accounts while the retired spouse begins withdrawals. Plan for how Social Security claiming will align with each spouse's retirement age. Tax planning becomes crucial, use the working spouse's income to offset the retired spouse's withdrawals strategically, and review your safe withdrawal rate across the entire household.
How does divorce or remarriage affect retirement income planning for couples?
Divorce has major implications for Social Security benefits, retirement account division, and beneficiary designations. Depending on marriage length, an ex-spouse may be entitled to spousal or survivor benefits. Remarriage can affect Social Security eligibility and may require updating beneficiaries on 401(k), IRA, and insurance policies. If remarrying, review your entire retirement income plan with a financial advisor to ensure accounts reflect your current intentions and protect your family's future.
What retirement income replacement ratio should couples aim for?
Most couples aim for 70-80% of pre-retirement income, though this varies based on lifestyle and expenses. Calculate your specific household expenses in retirement, then work backward to determine required income. Factor in Social Security, pensions, and investment withdrawals. An income replacement ratio helps you assess retirement readiness and ensure your safe withdrawal rate from savings is sustainable across both spouses' lifespans.
Additional Resources:
[EXTERNAL_LINK: Social Security Administration retirement benefits guide | ssa.gov]
[EXTERNAL_LINK: Medicare enrollment deadlines and coverage options | medicare.gov]
[EXTERNAL_LINK: IRS guidance on required minimum distributions and retirement account coordination | irs.gov]