 ultimate-guide
Medicare Enrollment Deadlines for Seniors: 2026 Guide
Table of Contents
- Understanding Medicare Enrollment Deadlines
- Initial Enrollment Period: Your First Chance to Enroll
- Medicare Annual Enrollment Period Dates and What Changes
- Special Enrollment Periods and Qualifying Life Events
- Understanding Medicare Part B Late Enrollment Penalty Costs
- Coverage Start Dates and Enrollment Timing
- Preparing for Enrollment: A Practical Checklist
- Frequently Asked Questions
Last Updated: August 13, 2026
Understanding Medicare Enrollment Deadlines
Medicare enrollment deadlines are fixed windows during which you can sign up for Medicare coverage without facing potential penalties or gaps in protection. Missing these deadlines can result in permanent penalties, delayed coverage, and unnecessary out-of-pocket costs that follow you for life.
Medicare has several enrollment deadlines, each tied to different circumstances and life situations. Understanding which deadline applies to you is the first step toward securing affordable, continuous coverage in retirement. A missed deadline can trigger a Medicare late enrollment penalty that increases your premiums permanently, a financial impact that compounds over decades.
Initial Enrollment Period: Your First Chance to Enroll
Your Initial Enrollment Period (IEP) is a seven-month window centered on your 65th birthday month. It begins three months before the month you turn 65 and ends three months after. This is your first and most important opportunity to enroll in Medicare Parts A and B.
Most people qualify for premium-free Part A based on their or their spouse's work history. Part B requires a monthly premium, and missing your IEP deadline means you'll face a lifelong late enrollment penalty if you delay enrollment beyond this window.
If your birthday is June 15, your Initial Enrollment Period runs from March through September. You can enroll any time during those seven months, and your coverage will begin on the first day of the month in which you turn 65 (or the following month if you enroll after your birthday month).
What happens if you miss your IEP? You can still enroll during the General Enrollment Period, but you'll face a 10% premium penalty on Part B for each year you delayed enrollment. That penalty is permanent and never goes away.
The only exception is if your employer plan is considered creditable coverage, meaning it provides at least as much coverage as Medicare. If you have creditable coverage through an employer, you may be able to delay Part B enrollment without penalty, but you must verify this status with your employer's benefits administrator before relying on it.
Consider starting your enrollment process at least two months before your IEP begins.
Medicare Annual Enrollment Period Dates and What Changes
The Medicare Annual Enrollment Period (AEP) runs from October 15 through December 7 each year. During this window, anyone already enrolled in Medicare can make changes to their coverage for the following year. This is the most common time for beneficiaries to switch between Original Medicare and Medicare Advantage plans, or to change their prescription drug coverage.
AEP is distinct from your Initial Enrollment Period. If you missed your IEP, you cannot use AEP to enroll in Medicare for the first time. AEP is only for people already covered by Medicare who want to modify their existing coverage.
During AEP, you can:
- Switch from Original Medicare to a Medicare Advantage plan
- Switch from a Medicare Advantage plan back to Original Medicare
- Change your prescription drug plan (Part D)
- Change your Medigap supplemental insurance
- Enroll in a new Medicare Advantage plan with different benefits
Coverage changes made during AEP take effect January 1 of the following year. Insurance companies also send "Annual Notice of Change" documents during this period, detailing any changes to premiums, deductibles, copays, and formularies for the upcoming year. A plan you chose last year may have significantly different costs or coverage this year.
Special Enrollment Periods and Qualifying Life Events
Special Enrollment Periods (SEPs) are windows outside of the standard enrollment periods that open when you experience specific life-changing events. If you qualify for a SEP, you can enroll in Medicare or make changes to your existing coverage without waiting for the next Annual Enrollment Period.
Qualifying life events that trigger a Special Enrollment Period include:
- Loss of employer-sponsored coverage (including COBRA)
- Loss of coverage through a spouse's employer plan
- Moving to a different state or service area
- Changes in your Medicaid eligibility
- Turning 65 while still employed with creditable employer coverage
- Divorce or death of a spouse
- Becoming eligible for Medicaid or CHIP
- Losing eligibility for Medicaid or CHIP
Each qualifying event comes with its own enrollment window, typically 60 days from the date the event occurs. Documenting the date of your qualifying event is critical.
A common mistake is assuming that any major life change qualifies for a SEP. Retirement alone does not trigger a Special Enrollment Period. You must experience one of the specific qualifying events listed above.
Understanding Medicare Part B Late Enrollment Penalty Costs
The Medicare Part B late enrollment penalty is a permanent increase to your monthly premium if you delay enrolling in Part B beyond your Initial Enrollment Period without qualifying for a Special Enrollment Period or having creditable coverage.
The penalty structure is straightforward: you pay an additional 10% of the standard Part B premium for each 12-month period you could have enrolled but didn't. If you delay enrollment for three years, you pay a 30% penalty on top of your regular premium. That penalty follows you for the rest of your life.
The penalty calculation compounds over time. For someone who delays enrollment by 5 years and lives another 20 years in retirement, they'll pay tens of thousands of dollars in unnecessary premiums.
The only way to avoid this penalty is to enroll during your Initial Enrollment Period, qualify for a Special Enrollment Period, or have creditable coverage through an employer or spouse's employer plan. There are no exceptions, no appeals, and no way to have the penalty waived once it's applied.
Coverage Start Dates and Enrollment Timing
Understanding when your coverage actually begins is just as important as knowing the enrollment deadlines. Coverage start dates depend on when you enroll and which enrollment period you're using.
If you enroll during your Initial Enrollment Period, coverage begins on the first day of the month in which you turn 65. If you enroll after your birthday month but still within your IEP, coverage begins the first day of the month following your enrollment.
For the Annual Enrollment Period, any changes you make between October 15 and December 7 take effect on January 1 of the following year. This is a fixed date regardless of when during AEP you enroll.
Special Enrollment Periods have variable start dates depending on the qualifying event. Generally, coverage begins the first day of the month following your enrollment. The specific start date will be documented in your SEP approval notice.
Timing matters for your financial planning. If you're retiring mid-year and losing employer coverage, you need to understand exactly when your Medicare coverage begins and when your employer coverage ends. A gap of even a few days can result in uninsured status.
New Insight Financial can help coordinate your retirement date with your Medicare enrollment to ensure seamless coverage transition.
Preparing for Enrollment: A Practical Checklist
Successful Medicare enrollment starts with preparation. Gathering the right documents and information before you begin the enrollment process eliminates confusion and prevents costly mistakes.
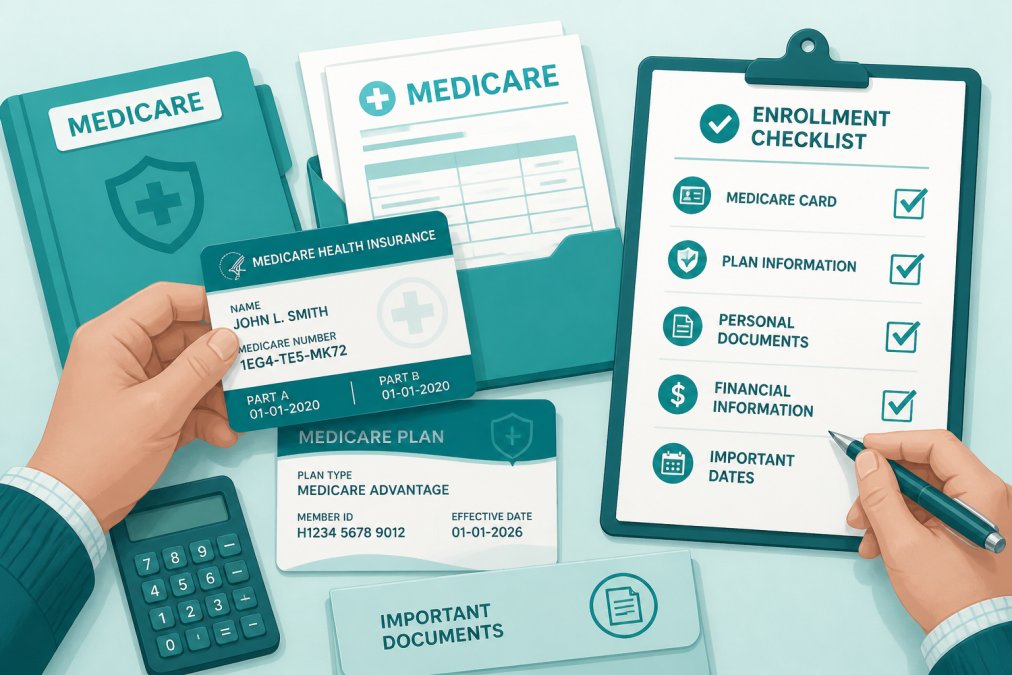
Before you enroll, gather these items:
- Your Social Security number
- Proof of citizenship or legal residency
- Information about any current health insurance coverage (employer plans, COBRA, individual plans)
- List of current medications and prescriptions
- List of doctors and specialists you currently see
- Information about any employer group health plans (yours or your spouse's)
- Documentation of creditable coverage if applicable
- Your Medicare card once you receive it (you'll need this for Part D enrollment)
Review your health and medication needs:
Medicare plans vary significantly in their prescription drug coverage and provider networks. Before enrolling, list all your current medications and identify which plans cover them at the lowest cost. Similarly, if you see specialists regularly, verify that your preferred doctors are in-network for any plan you're considering.
Understand your enrollment options:
You have two main paths through Medicare: Original Medicare (Parts A and B) with optional supplemental coverage, or Medicare Advantage (Part C). Original Medicare is administered by the federal government and accepted by virtually all Medicare providers nationwide. You can see any doctor who accepts Medicare without needing referrals. However, you're responsible for deductibles and coinsurance, which is why many people purchase Medigap supplemental insurance.
Medicare Advantage plans are run by private insurance companies and often include prescription drug coverage (Part D) bundled into one plan. These plans typically have lower premiums than Original Medicare plus Medigap, but they usually have network restrictions and may require referrals to see specialists.
Document your current coverage status:
If you're currently covered by an employer group health plan, document this clearly. Write down the plan name, your employer, the effective date of coverage, and any information about whether the plan is considered creditable coverage. This documentation becomes important if you ever need to prove you had continuous coverage or if you need to appeal a late enrollment penalty decision.
Set enrollment reminders:
Create calendar reminders for key dates:
- Three months before your 65th birthday (IEP begins)
- Your 65th birthday month
- Three months after your 65th birthday (IEP ends)
- October 1 each year (time to review Annual Notice of Change)
- October 15 each year (AEP begins)
- December 7 each year (AEP ends)
| Enrollment Period | Dates | Who Can Enroll | Coverage Start Date |
|---|---|---|---|
| Initial Enrollment Period | 3 months before to 3 months after 65th birthday | First-time Medicare enrollees | 1st of month you turn 65 (or following month if enrolled after birthday month) |
| Annual Enrollment Period | October 15 - December 7 | Current Medicare beneficiaries | January 1 following enrollment year |
| Special Enrollment Period | 60 days from qualifying event | Those with qualifying life events | Varies by event; typically 1st of following month |
| General Enrollment Period | January 1 - March 31 | Anyone not enrolled | May 1 following enrollment period |
Navigating Medicare enrollment deadlines for seniors doesn't have to be stressful. The key is understanding which deadline applies to your situation and taking action before it passes. New Insight Financial provides guidance to help retirees like you understand these complex enrollment periods and coordinate them with your overall retirement strategy. Our personalized approach ensures you're not just enrolled in Medicare, you're enrolled in the right plan for your health needs and financial situation. Get started today with a consultation that covers your Medicare options, enrollment timeline, and how this fits into your comprehensive retirement plan.
Frequently Asked Questions
What happens if you don't enroll in Medicare at 65?
Missing your Initial Enrollment Period without a valid reason triggers a Medicare Part B late enrollment penalty. This permanent 10% penalty applies for each full 12-month period you delay enrollment after your eligibility date. For example, if you wait three years to enroll, you'll pay a 30% penalty on your Part B premiums for life. The penalty compounds annually, making early enrollment financially critical.
What is the deadline to enroll in Medicare for 2026?
Your enrollment deadline depends on when you become eligible. The Initial Enrollment Period spans three months before, the month of, and three months after your 65th birthday. The Annual Enrollment Period runs October 15 through December 7 each year for coverage starting January 1. Special Enrollment Periods vary by qualifying event, typically offering 60 days to enroll.
Can you enroll in Medicare anytime during the year?
No. You can only enroll during specific windows: your Initial Enrollment Period (around your 65th birthday), the Annual Enrollment Period (October 15-December 7), or a Special Enrollment Period if you experience a qualifying life event like losing employer-sponsored coverage or moving. Enrolling outside these windows may result in coverage delays and late enrollment penalties.
How does the Medicare Part B late enrollment penalty work?
The Medicare Part B late enrollment penalty equals 10% of the standard Part B premium for each full 12-month period you delay enrollment. This penalty stays with you permanently, even if you eventually enroll. It only goes away if you have creditable coverage (like employer group health plan coverage) during your delay, which protects you from the penalty.