 ultimate-guide
Managing Market Risk in Retirement: A 2026 Guide
Table of Contents
- Why Market Risk Matters More in Retirement
- Understanding Sequence of Returns Risk
- Asset Allocation and Diversification Strategies for Retirees
- Retirement Portfolio Rebalancing Strategies
- How to Hedge Against Inflation in Retirement
- Safe Withdrawal Rates and Dynamic Spending Rules
- Tax-Efficient Withdrawal Sequencing and Social Security Optimization
- Staying Disciplined: Behavioral Finance in Market Downturns
- Frequently Asked Questions
Last Updated: August 15, 2026
Why Market Risk Matters More in Retirement
The transition from earning a paycheck to drawing down your portfolio is one of the most dangerous periods for your finances. In your working years, you could ride out a bear market because you had income flowing in. In retirement, you're withdrawing money while markets decline, creating a compounding problem that can permanently damage your financial security.
A market downturn in your first five years of retirement can be catastrophic in ways that a downturn at age 75 might not be. The sequence matters enormously. New Insight Financial works with retirees to understand this timing risk and build portfolios that account for it. The goal isn't to eliminate market risk entirely, that's impossible and would limit your returns. The goal is to structure your portfolio so that market volatility doesn't force you into bad decisions when you need income most.
Running out of money at 85 or 90 stems directly from how you manage market risk during the distribution phase. A poorly structured portfolio can turn a temporary market decline into a permanent loss of purchasing power.
Understanding Sequence of Returns Risk
Sequence of returns risk is the danger that market returns arrive in an unfavorable order during your retirement years. If you experience strong returns early in retirement, you can sustain withdrawals comfortably. If you hit a bear market in your first few years, you're forced to sell assets at depressed prices to fund living expenses, locking in losses and reducing the capital available to recover when markets rebound.
Imagine two retirees with identical 30-year returns of 7% annually. One experiences strong returns in years 1-5, then lower returns later. The other faces a bear market in years 1-5, then strong recovery. The first retiree ends with significantly more wealth, despite identical long-term returns. The timing of when you experience losses versus gains fundamentally shapes your retirement outcome.
You can't control whether markets rise or fall in any given year. What you can control is how much of your portfolio is exposed to that volatility when you're actively withdrawing funds. A common mistake is maintaining the same asset allocation throughout retirement. If you held 60% stocks at age 50, holding 60% stocks at 75 while withdrawing 5% annually exposes you to unnecessary sequence risk.
The solution involves restructuring your portfolio around your cash flow needs. If you need to withdraw $40,000 this year, ideally that money should already be in cash or stable value funds, not in equities that might be down 20%. This bucketing approach directly addresses sequence of returns risk.
Asset Allocation and Diversification Strategies for Retirees
Your asset allocation in retirement should reflect your actual cash flow needs and your ability to weather market downturns without panic selling. The conventional wisdom of "100 minus your age" in stocks is outdated for most retirees. A 65-year-old with 30+ years ahead might hold 60-70% equities. A 75-year-old with modest withdrawals might hold 40%.
Diversification in retirement reduces the likelihood that you'll face a major market decline exactly when you need to access your portfolio. A portfolio of only stocks leaves you vulnerable to equity bear markets. A portfolio of only bonds leaves you vulnerable to inflation eroding your purchasing power over 30 years.
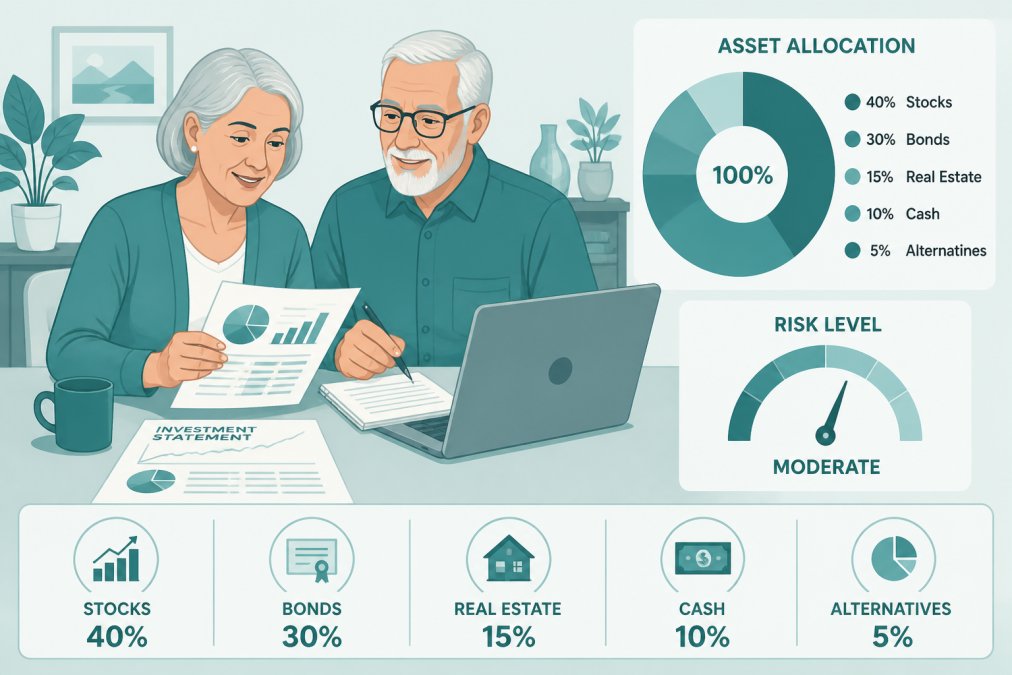
Consider these allocation approaches:
- Bucketing strategy: Hold 1-2 years of expenses in cash and short-term bonds, 3-10 years in intermediate bonds and balanced funds, and 10+ years in equities. This structure lets you avoid selling stocks during downturns.
- Core-satellite approach: Maintain a diversified core portfolio (60-70% of assets) with stable allocation, then use satellite positions for tactical adjustments based on market conditions.
- Dividend-focused equity allocation: Emphasize dividend-paying stocks and REITs that generate income, reducing reliance on portfolio liquidation for cash flow.
- International diversification: Include 15-25% in international equities to reduce home-country bias and capture growth from developed and emerging markets.
Your allocation should match your withdrawal schedule and risk tolerance. If you panic during a 25% market decline and sell equities at the bottom, your allocation was too aggressive. If inflation erodes your purchasing power by 30% over 20 years, your allocation was too defensive.
Retirement Portfolio Rebalancing Strategies
Rebalancing is the disciplined practice of selling winners and buying losers to maintain your target asset allocation. In retirement, rebalancing enforces the discipline to sell high and buy low, and ensures you don't drift into an unintended risk profile as markets move.
A common approach is annual rebalancing. If your target allocation is 60% stocks and 40% bonds, and stocks have appreciated to 65% of your portfolio, you sell some stocks and buy bonds to restore the 60-40 mix. This forces you to reduce equity exposure after a bull market and increase it after a bear market, when fear is highest.
In retirement, rebalancing can accomplish dual purposes with your withdrawal needs. If you need $50,000 for living expenses and your portfolio is overweighted in equities, you can withdraw the $50,000 from your equity positions, combining rebalancing with cash flow management.
Rebalancing frequency matters. Annual rebalancing is common and simple. Some advisors recommend rebalancing only when allocations drift beyond a threshold (e.g., when stocks exceed 65% or drop below 55%). This threshold-based approach reduces trading costs and taxes while maintaining discipline.
Tax-aware rebalancing is particularly important in taxable retirement accounts. Selling bonds with no gains is often preferable to selling appreciated stocks with embedded gains. This requires coordination across multiple accounts.
How to Hedge Against Inflation in Retirement
Inflation is a silent threat to retirement security. A 3% annual inflation rate cuts your purchasing power in half over 24 years. If you retire with $100,000 in annual spending power, that same lifestyle costs $202,000 in 24 years.
The primary hedge against inflation is equity exposure. Stocks have historically outpaced inflation over long periods. Companies can raise prices as inflation rises, protecting profit margins. Bonds offer no inflation protection, your $100,000 bond payment is worth less each year as inflation eroding its value.
This creates a tension in retirement: you need stability to fund near-term withdrawals, but you also need growth to protect long-term purchasing power. A 30-year retirement requires meaningful equity exposure even at age 70, because you'll need that growth to maintain your lifestyle in years 25-30.
Specific inflation hedges include:
- Treasury Inflation-Protected Securities (TIPS): These bonds adjust principal and interest payments based on inflation, protecting your real purchasing power.
- Dividend-growth stocks: Companies with histories of raising dividends provide both income and inflation protection as dividends grow over time.
- Real estate and REITs: Property values and rents typically rise with inflation, offering a tangible asset that preserves value.
- Commodities and commodity funds: Gold, oil, and agricultural commodities often appreciate during inflationary periods, though they're volatile short-term.
The balance depends on your time horizon. If you're 65 with a 30-year life expectancy, inflation protection is essential. If you're 85 with 10 years of expected withdrawals, inflation becomes less critical.
Safe Withdrawal Rates and Dynamic Spending Rules
The safe withdrawal rate represents the percentage of your portfolio you can withdraw annually and reasonably expect your money to last through retirement. The traditional rule of thumb is 4%: withdraw 4% of your starting portfolio in year one, then adjust that dollar amount for inflation each year.
This rule emerged from research showing that a 4% withdrawal rate from a balanced portfolio (60% stocks, 40% bonds) had a high probability of lasting 30 years historically. But "high probability" isn't certainty. A 4% withdrawal rate still carries meaningful sequence of returns risk, particularly if you encounter a bear market in your first five years.
Safe withdrawal rates depend on several factors:
- Portfolio allocation: A 50% stock portfolio supports a lower safe withdrawal rate than a 70% stock portfolio.
- Time horizon: A 20-year retirement supports higher withdrawal rates than a 40-year retirement.
- Flexibility: If you're willing to reduce spending during bear markets, you can sustain higher initial withdrawal rates.
- Income sources: Social Security and pension income reduce the burden on your portfolio, supporting higher withdrawal rates.
Dynamic spending rules offer an alternative to the static 4% approach. Instead of withdrawing a fixed inflation-adjusted amount every year, you adjust your spending based on portfolio performance. If your portfolio grew 8% and you spent 4%, you might increase spending by 3% the following year. If your portfolio declined 10%, you might reduce spending by 2%.
This approach reduces sequence of returns risk because you're automatically reducing withdrawals when your portfolio is under stress. The trade-off is spending uncertainty. Many retirees prefer a hybrid: a base spending level that's fixed, with discretionary spending that adjusts based on portfolio performance.
Tax-Efficient Withdrawal Sequencing and Social Security Optimization
Tax-efficient withdrawal sequencing determines which accounts you tap first to minimize lifetime taxes. The conventional advice is to withdraw from taxable accounts first, then tax-deferred accounts (IRAs and 401(k)s), then tax-free accounts (Roth IRAs). But this ignores the interaction between your withdrawals and Social Security taxation.
Social Security benefits are taxed based on your "combined income," which includes withdrawals from tax-deferred accounts. If you're withdrawing $80,000 from an IRA and receiving $30,000 in Social Security, your combined income might trigger taxation of 50-85% of your Social Security benefits. This creates a marginal tax rate higher than your ordinary income tax rate.
A more sophisticated approach considers the timing of withdrawals relative to your Social Security claiming age. If you delay Social Security from age 62 to age 70, your benefit increases by roughly 8% per year. During those delay years, you might withdraw more from taxable accounts (which have lower tax rates) and less from tax-deferred accounts. This reduces the tax burden on your future Social Security benefits.
Medicare premiums add another layer. Your Medicare Part B and Part D premiums are based on your modified adjusted gross income (MAGI) from two years prior. High withdrawals in one year can trigger higher premiums for two subsequent years. Tax-efficient sequencing accounts for this timing lag.
Implementing this requires coordination across multiple accounts and understanding your specific tax situation. New Insight Financial coordinates withdrawal sequencing with Social Security timing and Medicare planning to minimize your lifetime tax burden.
Staying Disciplined: Behavioral Finance in Market Downturns
The technical knowledge of how to manage market risk in retirement is worthless if you panic and abandon your strategy during a bear market. Most investors are their own worst enemy, they buy high and sell low. In retirement, this pattern is catastrophic because you're withdrawing funds simultaneously, amplifying losses.
The psychological challenge in retirement is acute because the stakes feel immediate. A 30% market decline when you're 65 and withdrawing funds feels existential. Your mind screams to sell stocks and move to cash. Your rational brain knows this locks in losses and derails your long-term plan.
Several behavioral strategies help:
- Pre-commitment: Establish your withdrawal strategy and rebalancing rules before a bear market hits. When fear peaks, you're following a plan you created in a rational state.
- Automated withdrawals: Set up automatic transfers from your portfolio to your checking account. This removes emotion from the process.
- Regular advisor contact: Talking to a trusted advisor during market stress provides perspective and reminds you that bear markets are temporary.
- Focus on cash flow, not portfolio value: During a downturn, stop checking your portfolio balance. Verify that your cash flow strategy is working and that you have enough money for the next 12 months of expenses.
Your biggest risk during a bear market isn't that your portfolio declines. It's that you'll make a permanent decision (selling stocks) based on a temporary emotion (fear). The market will recover. Your decision to sell at the bottom might not.
This is why the structure of your portfolio matters so much. If you've implemented a bucketing strategy with two years of expenses in cash, a bear market is psychologically manageable. You know you can fund your lifestyle for the next two years without touching stocks. That knowledge is powerful.
Managing market risk in retirement requires more than technical knowledge, it demands a structured approach that accounts for sequence of returns risk, inflation, taxes, and your own psychology. New Insight Financial specializes in building customized retirement plans that integrate these elements, from diversified asset allocation to tax-efficient withdrawal sequencing to behavioral coaching during market stress. The goal isn't perfection; it's building a retirement strategy resilient enough to survive market downturns while generating the income you need. Get started today with New Insight Financial and transform your retirement plan from a source of anxiety into a source of confidence.
Frequently Asked Questions
What is sequence of returns risk and how does it affect retirement?
Sequence of returns risk is the danger that poor investment returns early in retirement can permanently damage your portfolio. If markets decline when you're withdrawing money for living expenses, you're selling assets at low prices and may not recover even when markets rebound. This risk is highest in your first 5-10 years of retirement. Managing it requires a mix of conservative investments, adequate cash reserves, and flexible spending rules that let you reduce withdrawals during downturns.
How can I protect my retirement portfolio from inflation?
Inflation erodes purchasing power over decades of retirement. Include inflation-protected assets like Treasury Inflation-Protected Securities (TIPS), stocks with dividend growth potential, and real estate or commodities. Maintain modest equity exposure even in retirement, historically, stocks outpace inflation better than bonds. Review your spending annually and adjust withdrawals upward to match inflation. Social Security benefits adjust automatically for inflation, making them a valuable hedge for essential expenses.
What is the 4% rule and how does it relate to market risk?
The 4% rule suggests withdrawing 4% of your portfolio in year one of retirement, then adjusting that dollar amount for inflation annually. This approach historically sustained 30-year retirements through multiple bear markets. However, it assumes a diversified portfolio and doesn't account for individual circumstances like longevity, healthcare costs, or market timing. Dynamic spending rules, adjusting withdrawals based on current portfolio performance, may offer better protection during severe downturns while maintaining flexibility in strong years.
What are the most common retirement risks beyond market volatility?
Longevity risk (outliving your savings), inflation reducing purchasing power, healthcare costs, and sequence of returns risk are major concerns. Social Security provides inflation-adjusted income for essentials. Long-term care planning protects against catastrophic expenses. Tax-efficient withdrawal sequencing, drawing from taxable, traditional, and Roth accounts strategically, preserves wealth. Working with a financial professional to stress-test your plan against these scenarios helps ensure your portfolio survives unexpected challenges.