 How-to
How to Calculate Life Insurance Needs After Retirement
Quick Summary
Calculate life insurance needs after retirement by totaling the surviving spouse's annual spending gap over the years of coverage, plus debts and final expenses, then subtracting liquid assets and existing death benefits. Guaranteed survivor income such as Social Security and pension survivor options reduces the gap.
- Use the survivor's guaranteed income, not the deceased spouse's earned income, since paychecks stop at death.
- The survivor's spending gap is annual spending minus Social Security survivor benefits and any continuing pension or annuity payments.
- Base the years of coverage on the surviving spouse's life expectancy, not the deceased's.
- Count retirement accounts at after-tax value, since withdrawals are generally taxable.
- Recheck your numbers every few years or after major changes like a spouse's death or a debt payoff.
Table of Contents
- Why Retirees Still Need to Run the Numbers on Life Insurance
- Step 1: Gather Your Retirement Income and Asset Figures
- Step 2: Total Your Debts, Final Expenses and Income Gaps
- Step 3: Work Through a Retirement Needs Worksheet With Examples
- Using a Life Insurance Calculator and Coordinating Survivor Benefits
- Estate Liquidity, Taxes and Inheritance Goals
- Deciding Whether to Keep, Reduce or Drop Your Coverage
- Frequently Asked Questions
Why Retirees Still Need to Run the Numbers on Life Insurance
Last Updated: November 5, 2026
Many retirees assume life insurance is only for working families with mortgages and young kids. That assumption can leave a surviving spouse with gaps they never expected. Retirement is a stage where coverage decisions matter just as much, because income, debts and assets all shift once paychecks stop.
Life insurance needs after retirement are different from needs during working years. The main question is no longer how many years of paychecks to replace. It becomes how a surviving spouse will cover fixed costs, final expenses and taxes from pensions, Social Security survivor benefits and savings. Running the numbers once gives you a clear answer. Revisiting them every few years keeps that answer current.
This guide walks through a simple process. You will gather your figures, total your obligations, work through a worksheet with examples, and decide whether to keep, reduce or drop your coverage.
Step 1: Gather Your Retirement Income and Asset Figures
Start by listing every source of income and every asset you and your spouse hold. Accuracy here matters more than speed.
Collect these items:
- Social Security statements: Pull each spouse's estimate from the Social Security Administration. Check the official Social Security Administration website for current guidance.
- Pension details: Note the monthly benefit and whether it continues to a survivor under the payout option you chose.
- Retirement accounts: Record balances in IRAs, 401(k)s and similar accounts.
- Other savings and investments: Include brokerage accounts, savings and any annuities.
- Home equity: Note the estimated value of your home and any remaining mortgage balance.
Keep in mind that some income stops at death. A pension with no survivor option, or a Social Security benefit that drops to the larger spouse's amount, changes the picture. Write down what the surviving spouse would actually receive.
A common mistake is counting every dollar as available. Retirement accounts may carry income taxes when withdrawn, so list them at after-tax value where you can estimate it.
Step 2: Total Your Debts, Final Expenses and Income Gaps
Next, add up what your family would owe and what they would need to replace.
Debts and obligations to list:
- Mortgage or rent balance
- Credit cards, auto loans and personal loans
- Outstanding medical bills
- Any co-signed debts
Final expenses to estimate:
- Funeral and burial costs
- Legal and estate settlement fees
- Taxes owed at death
Ongoing income gaps:
Subtract the surviving spouse's guaranteed income from the household's regular monthly spending. The remainder is the monthly gap a policy might need to cover. Multiply that gap by the number of years the survivor expects to need support. Many planners use a rough horizon tied to the spouse's life expectancy, so the result is a starting estimate rather than a final figure.
Here is a simple way to organize the totals:
| Category | Example Amount | Your Amount |
|---|---|---|
| Outstanding debts | $60,000 | |
| Final expenses | $15,000 | |
| Monthly spending gap | $1,500 | |
| Years of gap coverage | 10 |
Add the debt and final expense totals, then add the monthly gap multiplied by the years. That sum is your starting point before subtracting assets.
Step 3: Work Through a Retirement Needs Worksheet With Examples
Now you bring the figures together. The goal is a transparent formula you can audit line by line, not a black-box calculator result.
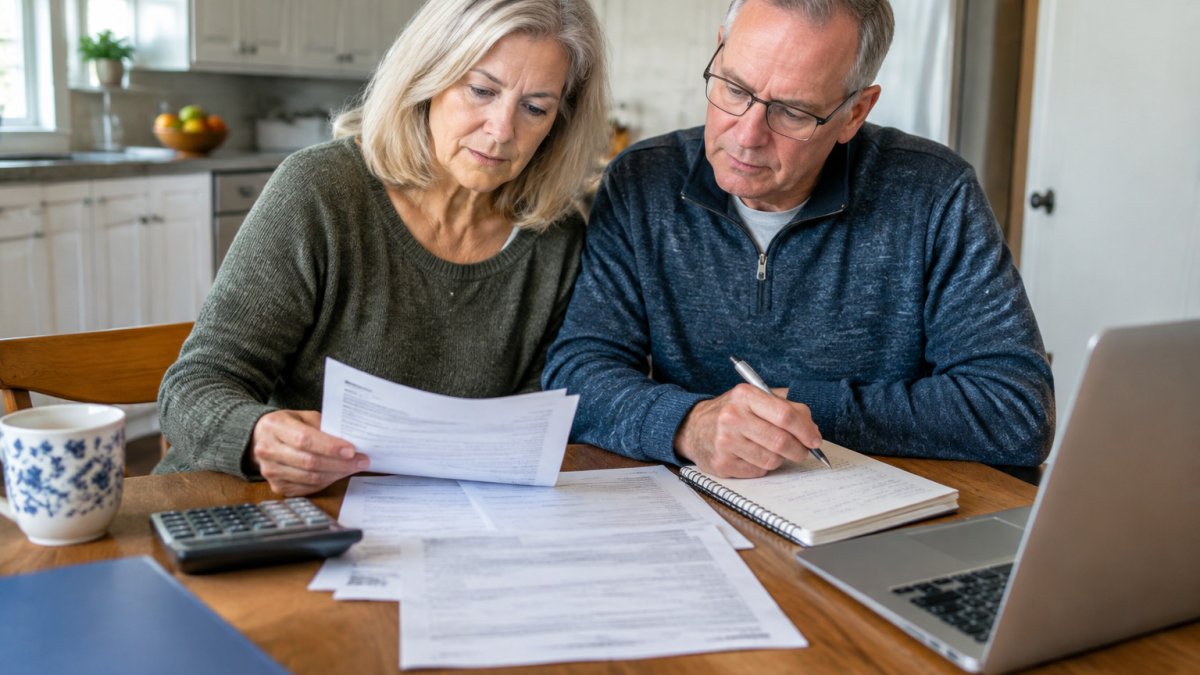
The retirement needs formula
Each term has a retirement-specific meaning:
- Survivor's annual spending gap: The surviving spouse's expected annual spending minus guaranteed survivor income (Social Security survivor benefit, any continuing pension, annuity payments with a survivor option). Do not include the deceased spouse's earned income, because it stops.
- Years of gap coverage: A planning horizon tied to the survivor's life expectancy, not the deceased's. A common pattern is to use the survivor's estimated lifespan minus current age, then stress-test with a longer horizon.
- Debts: Mortgage balance, auto and personal loans, credit cards, medical bills, and any co-signed obligations that survive.
- Final expenses: Funeral and burial costs, estate settlement and legal fees, and taxes owed at death.
- Estate liquidity reserve: Cash the estate needs to pay costs without forcing a sale of illiquid assets such as real estate or a family business.
- Liquid assets available: After-tax value of savings, brokerage accounts, and retirement accounts the survivor can access, plus home equity only if the survivor plans to downsize or borrow against it.
- Existing death benefit: The face amount of any policy already in force, net of any loans or outstanding premiums.
Worked example: The Carter household
A retired couple in their early 60s. One spouse has a pension with a 50% survivor option and both have Social Security.
| Line item | Amount |
|---|---|
| Survivor's annual spending | $72,000 |
| Guaranteed survivor income (Social Security survivor benefit + 50% pension) | $50,400 |
| Annual spending gap | $21,600 |
| Years of gap coverage (survivor age 62 to estimated 90) | 28 |
| Gap subtotal ($21,600 × 28) | $604,800 |
| Outstanding debts (mortgage remainder) | $40,000 |
| Final expenses | $15,000 |
| Estate liquidity reserve | $25,000 |
| Gross need | $684,800 |
| Liquid assets available to survivor (after-tax) | $180,000 |
| Existing life insurance death benefit | $100,000 |
| Estimated additional coverage need | $404,800 |
Calculation: $604,800 + $40,000 + $15,000 + $25,000 = $684,800. Subtract $180,000 in liquid assets and $100,000 in existing coverage to get $404,800.
Worked example: A single retiree with no dependents
A single retiree with no debts, $60,000 in final-expense and estate-settlement costs, and $250,000 in liquid assets may need little or no coverage.
Stress-test the assumptions
Change one input at a time and watch how the result moves. Shorten the years of coverage to the survivor's likely minimum lifespan, then extend it.
Using a Life Insurance Calculator and Coordinating Survivor Benefits
Most online life insurance calculators are built for working years. They ask for annual income and multiply by a factor, which overstates what a retired household needs because the deceased spouse's paycheck is no longer the thing being replaced.
Coordinate survivor income sources before you trust any calculator
The retirement-specific step competitors skip is stacking the survivor's income sources and removing double counting. Work through each source:
- Social Security survivor benefit: A surviving spouse generally receives the larger of the two benefits, not both. The survivor's own benefit may be replaced by the survivor benefit if it is higher. Confirm the actual survivor amount with the Social Security Administration before entering it.
- Pension survivor option: A single-life pension stops at death; a joint-and-survivor option continues a percentage (often 50%, 75%, or 100%) to the survivor. Check the payout option you elected, because a pension with no survivor option creates a gap the calculator must capture.
- Annuities: Only payments with a survivor or joint-life feature continue. A life-only annuity stops at death and should not be counted as survivor income.
- Retirement-account withdrawals: IRAs and 401(k)s pass to beneficiaries, but the survivor's sustainable withdrawal rate, not the full balance, is the income figure to use. Inherited-account rules depend on the beneficiary's relationship and the account type, so confirm the treatment before counting the dollars.
A coordination example
Suppose the surviving spouse's own Social Security benefit is $2,100 per month and the deceased spouse's benefit was $2,800 per month. The survivor generally steps up to the larger $2,800 benefit, not $4,900 combined.
When a calculator is enough and when it is not
A calculator is enough for a rough sanity check when the household has simple finances: one Social Security benefit, modest savings, and no estate liquidity concern.
For a deeper look at how income sources fit together, our guide on calculating retirement income from multiple sources walks through the details.
Estate Liquidity, Taxes and Inheritance Goals
Insurance proceeds can give heirs cash quickly. That matters when an estate holds mostly illiquid assets like real estate or a family business. Without cash on hand, heirs may need to sell property to pay estate costs.
Taxes add another layer. Estate tax rules and retirement account rules work differently from one another, and tax treatment depends on the specific situation. Inherited retirement accounts can carry their own tax consequences, and those rules depend on who inherits and how.
If leaving a legacy matters to you, coverage can fund it directly. Our article on how to claim tax benefits of long-term care insurance explains one area that often overlaps with inheritance planning. For spouses inheriting retirement accounts, tax implications of inherited retirement accounts for spouses covers the rules in more depth.
Keep your important papers organized as well. Many families struggle to locate policies and account details at the worst possible time. Our Generational Vault® service offers a secure online place to store essential documents so loved ones can find them when needed.
Deciding Whether to Keep, Reduce or Drop Your Coverage
Once you have a number, compare it to your current policy. Three outcomes are common:
- Keep: Your existing coverage roughly matches the gap you calculated.
- Reduce: Your gap has shrunk because debts were paid off or savings grew. A smaller policy may fit better.
- Drop: Your household has enough guaranteed income and assets to cover final costs and the survivor's needs.
Coverage may no longer be necessary when the surviving spouse can comfortably meet expenses without the death benefit. Check whether your policy is term or permanent. Term coverage ends after a set period. Permanent coverage can serve estate or legacy goals, and it typically costs more. Compare premiums against the value each option provides.
Many people find this decision easier with a conversation. The Life by Design Conversation™ at New Insight Financial aligns your money decisions with your values and goals. You can also explore term life insurance options with us to see what fits your situation.
Revisit your numbers every few years or after major changes such as a spouse's death, a move, or a large debt payoff. Getting started is simple, and the worksheet you completed today gives you a head start.
Frequently Asked Questions
How much life insurance do I need after retirement?
There is no single amount that fits every retiree. Many people start by listing the income a surviving spouse would lose, subtracting the Social Security survivor benefits and pension payments that would continue, then adding outstanding debts and final expenses such as funeral costs. Savings and investments that could cover the remaining gap reduce the coverage you need. Because these figures change with age, health and spending, review the calculation every few years and after major life events like paying off a mortgage.
Do I really need life insurance after retirement?
Not always. If your savings and pension cover your spouse's income for life and you have no debts or dependents, you may need little or no coverage. Life insurance is most useful for covering a spouse who would lose a pension or Social Security income, for final expenses, or for leaving an inheritance or estate liquidity. A retiree with a large estate may still want coverage to pay estate taxes without selling assets. Review your situation with a qualified professional before deciding.
Should I count retirement savings and Social Security when estimating life insurance needs?
Yes, both reduce the coverage you need, but they should be counted carefully. Social Security survivor benefits depend on the deceased spouse's work record and your own age, and the exact amounts should be confirmed with the Social Security Administration at ssa.gov. Retirement account balances can be drawn down, so only count the portion that could realistically support a surviving spouse over their expected lifespan, and remember that taxes may reduce withdrawals from traditional accounts.
How can a life insurance calculator help estimate coverage after retirement?
A life insurance calculator asks for income, debts, dependents, savings and final expense estimates, then produces a suggested coverage amount. It is a useful starting point for comparing scenarios, such as coverage that replaces a spouse's lost pension versus coverage that only pays final costs. Treat the result as an estimate rather than a recommendation, because most calculators do not account for taxes, inflation or survivor benefit rules. Check the inputs against your actual statements before relying on the output.



