 comparison
Financial Planning Services: A 2026 Comparison
Table of Contents
- What Financial Planning Services Actually Include
- How Fee-Only Financial Advisors Differ from Commission-Based Models
- Understanding Financial Planning Cost Structures
- What Fiduciary Financial Advisor Requirements Mean for You
- Comparing Financial Planning Services: Hybrid vs. Robo-Advisor vs. Full-Service
- How to Choose the Right Financial Planning Service for Your Situation
- Retirement Income Planning and Withdrawal Strategy Protection
- Frequently Asked Questions
Last Updated: August 12, 2026
What Financial Planning Services Actually Include
Financial planning services are comprehensive advisory solutions that help individuals and couples organize finances, set goals, and create actionable strategies to achieve financial security. They typically include investment strategy, retirement income planning, tax optimization, estate planning guidance, and risk management through insurance and diversification.
At New Insight Financial, we understand that retirement planning isn't just about managing money, it's about converting accumulated wealth into a reliable income stream while protecting against the four major retirement financial risks: longevity risk, market volatility, inflation, and unexpected healthcare costs. A true financial planning service should address your complete financial picture: where your money is, how it's invested, what you'll need in retirement, how taxes will affect your withdrawals, and what happens to your family if something unexpected occurs.
How Fee-Only Financial Advisors Differ from Commission-Based Models
The fee structure of your financial advisor determines whether their incentives align with yours. A fee-only financial advisor charges you directly for advice, either a flat fee, hourly rate, or percentage of assets under management (AUM), and doesn't earn commissions from selling products. This eliminates the fundamental conflict of interest: the advisor has no financial incentive to recommend one investment product over another or to trade more frequently than necessary.
Commission-based advisors earn money when they sell you products, creating structural pressure to prioritize products that pay higher commissions, which may not align with your best interests.
The fiduciary standard is the legal requirement that an advisor must act in your best interest, putting your interests ahead of their own financial gain. Fee-only advisors operating under a fiduciary duty are legally required to make recommendations based on what's best for you. Studies consistently show that fee-only advisors tend to recommend more tax-efficient strategies and lower-cost investments because they're not incentivized to push higher-margin products. Over a 20-year retirement, this alignment can mean tens of thousands of dollars in your pocket.
Understanding Financial Planning Cost Structures
Financial planning services use three primary cost models:
Percentage of Assets Under Management (AUM) is the most common model for ongoing advisory relationships, typically ranging from 0.25% to 1.5% depending on service level and account size. For a $500,000 portfolio at 0.50% AUM, you'd pay $2,500 annually. This model aligns incentives because the advisor benefits when your portfolio grows.
Flat Fee models charge a fixed annual amount regardless of account size, typically $3,000-$10,000 depending on complexity. This removes the incentive to oversell account size and works well for clients with moderate wealth who want transparent, predictable costs.
Hourly Rates typically range from $150 to $500 per hour depending on experience and location. This model suits one-time planning projects or clients who want occasional advice without ongoing management.
When comparing cost structures, calculate total annual costs across all fees and investment expenses, then project over 10-20 years. A 0.50% AUM fee on a $500,000 portfolio ($2,500 annually) adds up to $50,000 over 20 years, money that could have stayed invested and compounded.
What Fiduciary Financial Advisor Requirements Mean for You
A fiduciary financial advisor is legally required to act in your best interest and to disclose any conflicts of interest. This means recommending investments and strategies based on what's genuinely best for you, not what generates the highest commission or fee.
The critical distinction is between fiduciaries and non-fiduciaries. A non-fiduciary advisor only needs to meet a "suitability" standard, meaning the recommendation just needs to be reasonably appropriate for you, not necessarily the best option available. An advisor could recommend a mediocre investment that's technically suitable without violating suitability rules.
However, the fiduciary standard has important limitations. Being a fiduciary doesn't mean an advisor has perfect judgment or that their recommendations will always work out. It means they're legally obligated to act in your interest and make recommendations based on professional expertise.
Additionally, not all advisors operate under a fiduciary standard in all contexts. Some are fiduciaries only when providing investment advice, but not when recommending insurance products. This is why asking "Are you a fiduciary 100% of the time?" is essential, the answer reveals whether they have consistent legal obligations to prioritize your interests.
Comparing Financial Planning Services: Hybrid vs. Robo-Advisor vs. Full-Service
The market for financial planning services has fragmented into three distinct models, each serving different needs and budgets.
Hybrid Advisory Services
Hybrid financial planning services combine automated portfolio management with access to human advisors. Vanguard Personal Advisor Services exemplifies this model, offering personalized financial planning, automated portfolio management using low-cost funds and ETFs, and access to human financial advisors via phone, email, or video. The advisory fee starts at 0.30% of assets under management annually for accounts with at least $50,000, significantly lower than traditional full-service advisors (typically 0.75-1.5% AUM) while providing more personalized guidance than pure robo-advisors.
The limitation is depth. Hybrid advisors typically focus on investment management and basic planning rather than comprehensive retirement income strategy, Medicare navigation, or complex estate planning.
Robo-Advisor Platforms
Robo-advisors use algorithms to build and manage diversified portfolios based on your risk tolerance and goals. Fidelity Go offers automated investing starting with no minimum, charging zero advisory fees for balances under $25,000, then 0.35% annually for larger accounts. Schwab Intelligent Portfolios charges zero advisory fees entirely, with only underlying ETF operating expenses (averaging 0.12-0.13% annually).
Robo-advisors excel for straightforward investing: young professionals building wealth, people who want hands-off management, or those with simple financial situations. They fail when your retirement requires income planning, tax coordination across multiple accounts, or strategies to manage sequence-of-returns risk.
Full-Service Retirement Planning
Full-Service financial planning services provide comprehensive retirement income planning, tax optimization, estate planning coordination, insurance analysis, and ongoing strategic guidance. New Insight Financial specializes in retirement planning for individuals and couples navigating the transition from working years to retirement. Our service includes income planning that coordinates Social Security claiming strategy, Medicare enrollment guidance, tax-efficient withdrawal sequencing, and protection against the four major retirement financial risks.
Full-service advisors typically charge 0.75-1.25% AUM or flat fees ranging from $3,000-$10,000+ annually, depending on complexity. For someone with $500,000-$2,000,000 in retirement assets, a full-service advisor's fee can be justified if their strategies generate tax savings or income optimization worth more than you're paying.
How to Choose the Right Financial Planning Service for Your Situation
Selecting the right financial planning service depends on three factors: account complexity, specialized expertise you need, and your preference for human interaction versus automation.
Assess Your Account Consolidation Needs
Start by mapping your current financial situation. How many retirement accounts do you have? Account consolidation is critical because withdrawal strategy, tax efficiency, and risk management all depend on viewing your complete financial picture. If your money is fragmented across multiple institutions, most robo-advisors can't help you.
New Insight Financial helps clients consolidate accounts and build a unified withdrawal strategy that treats all your assets as an integrated portfolio. The order in which you withdraw from different account types (taxable, traditional IRA, Roth) dramatically affects your long-term tax bill.
If you have straightforward finances with one or two accounts and simple income needs, a robo-advisor or hybrid service handles consolidation adequately. If your accounts are scattered or you have complex coordination needs, you need a full-service advisor who can see everything and build a truly integrated plan.
Evaluate Specialized Expertise You Need
Different life situations require different expertise. If you're transitioning from working to retirement, you need expertise in retirement income planning and withdrawal strategy. If you have significant real estate or business interests, you need tax planning expertise. If you're concerned about long-term care costs, you need someone who understands insurance and Medicaid planning.
Medicare navigation is a specific expertise that many financial advisors don't possess. Getting Medicare enrollment wrong costs you thousands in penalties and missed benefits. New Insight Financial includes Medicare guidance as part of comprehensive retirement planning because it's inseparable from your overall income strategy.
Ask potential advisors directly: "What's your specific experience with [your situation]?" Listen for concrete examples and specific strategies, not generic answers.
Verify Credentials and Fiduciary Status
The most relevant credential for financial planning is Certified Financial Planner (CFP), which requires education, examination, and ongoing continuing education. A CFP has demonstrated knowledge across all areas of financial planning and operates under a fiduciary standard.
Ask three specific questions:
- "Are you a fiduciary 100% of the time, or only in certain contexts?"
- "How do you charge for your services, and what are all the fees I'll pay annually?"
- "Can you provide references from clients with situations similar to mine?"
Check credentials through official sources. CFP certification can be verified through the Certified Financial Planner Board of Standards. Fiduciary status and regulatory history can be checked through FINRA's BrokerCheck or the SEC's Investment Adviser Public Disclosure database.
Retirement Income Planning and Withdrawal Strategy Protection
The transition from accumulating wealth to distributing it requires a fundamentally different strategy. Retirement income planning addresses how you'll convert your portfolio into reliable income while managing the risks that threaten that income stream.
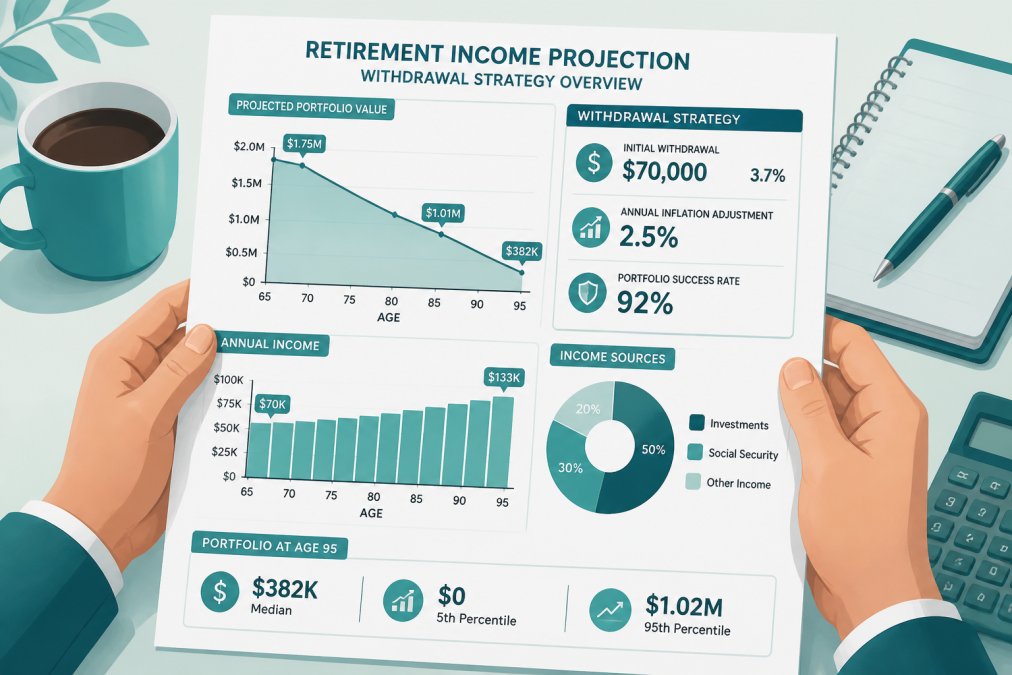
Withdrawal strategy determines the order and timing of withdrawals from different account types. A strategic approach considers tax brackets, required minimum distributions, Social Security timing, Medicare premiums (which are income-based), and the sequence in which you draw from taxable, traditional, and Roth accounts. The naive approach, withdrawing from whatever account is most convenient, often costs tens of thousands in unnecessary taxes.
Sequence-of-returns risk is the danger that poor market returns early in retirement force you to sell assets at depressed prices to fund living expenses, locking in losses and reducing the portfolio's recovery potential. A comprehensive retirement income plan addresses this through diversification, withdrawal sequencing that minimizes forced selling during downturns, and potentially conservative positioning for near-term expenses.
Many people approach retirement assuming they'll simply withdraw 4% of their portfolio annually and adjust for inflation. This rule of thumb provides rough guidance but ignores individual circumstances. Someone with significant Social Security income can withdraw less from their portfolio. Someone with large healthcare expenses or a shorter life expectancy needs a different strategy.
New Insight Financial builds withdrawal strategies tailored to your specific situation, accounting for your income sources, tax situation, risk tolerance, and life expectancy. We address the four major retirement financial risks: longevity risk, market risk, inflation risk, and healthcare cost risk.
The cost of getting this wrong is significant. A suboptimal withdrawal strategy can cost 10-15% of your portfolio value over a 30-year retirement through unnecessary taxes, forced selling during downturns, or running out of money too early. The cost of professional guidance that prevents these mistakes typically pays for itself many times over.
Choosing a financial planning service is fundamentally about matching your needs to the right expertise level and service model. For couples approaching or in retirement, the complexity of coordinating income sources, managing taxes, and protecting against market risk justifies professional guidance. New Insight Financial provides comprehensive retirement planning that addresses income strategy, tax efficiency, and the specific risks that threaten retirement security. Get started today and discover how integrated retirement planning can transform uncertainty into a reliable financial roadmap.
| Service Model | Best For | Key Advantage | Primary Limitation |
|---|---|---|---|
| Robo-Advisor | Simple situations, young investors, hands-off preference | Lowest cost, automated management | Limited to basic investing, no retirement income planning |
| Hybrid Advisory | Moderate complexity, want some human guidance | Lower cost than full-service, access to advisors | Limited depth for complex tax or estate situations |
| Full-Service Planning | Retirement transition, complex accounts, multiple income sources | Comprehensive strategy, integrated tax planning, retirement income focus | Higher fees, requires significant assets to justify cost |
Frequently Asked Questions
What is the difference between a fiduciary and a non-fiduciary financial advisor?
A fiduciary advisor is legally required to act in your best interest at all times. A non-fiduciary advisor only needs to recommend suitable products, not necessarily the best ones for you. This distinction matters significantly when choosing financial planning services. Fiduciary advisors must disclose conflicts of interest and prioritize your goals over their commissions. Many financial planning services operate under fiduciary standards, though you should verify this explicitly before hiring.
How much money do you need to start working with a financial advisor?
Minimums vary widely across financial planning services. Some robo-advisors accept accounts as small as $5,000 or even $10, while hybrid advisory services often require $25,000 to $50,000 minimum investments. Full-service retirement planning firms may require $100,000 or more in assets under management. Your situation, especially if you're consolidating multiple old accounts, may affect which services are accessible to you. Contact advisors directly about their specific minimums.
Is it worth paying for a financial planner if I've managed my own investments successfully?
Even experienced investors benefit from professional financial planning services, especially approaching retirement. Advisors bring specialized expertise in tax-efficient withdrawal strategies, Medicare navigation, Social Security timing optimization, and estate planning, areas where mistakes can cost thousands. They also provide behavioral coaching during market downturns and help stress-test your retirement income projections against real-world scenarios like healthcare costs and longevity risk. The value often exceeds the cost when considering comprehensive retirement security.
What should I ask a financial advisor before hiring them?
Ask whether they operate under a fiduciary standard, how they're compensated (fee-only, commission, or hybrid), their specific experience with retirement income planning and Medicare navigation, how they handle account consolidation from multiple sources, and how they stress-test withdrawal strategies against market downturns. Request references from clients in similar life situations. Ask about their approach to behavioral finance and how they help clients stay disciplined during volatility. Verify their credentials and check for any regulatory complaints.