 ultimate-guide
Financial Legacy Planning Services: A 2026 Guide
Table of Contents
- What Is Financial Legacy Planning?
- Estate Planning vs Legacy Planning: Understanding the Difference
- Key Components of a Comprehensive Legacy Strategy
- Charitable Giving Tax Benefits: Maximizing Your Impact
- Building Your Legacy Planning Checklist
- How to Choose a Legacy Planning Advisor
- Why Professional Financial Legacy Planning Matters
- Getting Started with Your Legacy Plan Today
- Frequently Asked Questions
Last Updated: August 9, 2026
What Is Financial Legacy Planning?
Financial legacy planning is the process of organizing your assets, values, and wishes to ensure your family is protected and your legacy continues according to your vision. Unlike simple estate planning, which focuses on what happens to your assets after death, legacy planning takes a broader view, addressing how you want your wealth to benefit your loved ones, your community, and causes you care about during your lifetime and beyond.
At New Insight Financial, we understand that legacy planning encompasses income strategies, tax efficiency, charitable goals, and family communication. It's about converting decades of accumulated wealth into lasting impact. The best legacy plans align your financial decisions with your personal values, ensuring every dollar works toward outcomes that matter to you.
Estate Planning vs Legacy Planning: Understanding the Difference
Estate planning is the legal and financial process of arranging your assets and designating beneficiaries to minimize taxes and probate costs after your death. It focuses on mechanics: wills, trusts, powers of attorney, and healthcare directives.
Legacy planning is broader. It includes estate planning as a foundation but extends far beyond it. Legacy planning asks deeper questions: What values do you want to pass to your children? How should your wealth be distributed across generations? What charitable causes deserve your support? How do you want to be remembered?
The distinction matters because many people complete basic estate planning, they sign a will, name beneficiaries, and believe they're done. Estate planning handles the legal transfer of assets. Legacy planning ensures those assets serve your actual life goals.
Consider this scenario: A couple completes a will that splits their $2 million estate equally between two adult children. That's estate planning. But what if one child is financially responsible and the other struggles with money management? What if they want to fund their grandchildren's education or support a nonprofit they've championed for decades? Estate planning alone doesn't address these nuances. Legacy planning does.
Another key difference is timing. Estate planning activates after death. Legacy planning is active right now. It shapes your investment decisions, tax strategies, and insurance choices during your working and early retirement years.
Key Components of a Comprehensive Legacy Strategy
A complete legacy strategy rests on five interconnected pillars: asset organization, wealth transfer planning, tax efficiency, family communication, and values alignment.
Wealth Transfer and Beneficiary Designations
Your beneficiary designations are among the most powerful legacy planning tools available, yet many people overlook them or leave them outdated. Beneficiary designations on retirement accounts, life insurance policies, and transfer-on-death accounts bypass your will entirely, they pass directly to whoever you name.
This creates both opportunity and risk. The opportunity: you can direct specific assets to specific people outside the probate process, saving time and money. The risk: if your designations don't align with your overall legacy plan, you can accidentally disinherit someone or create unintended tax consequences.
A common mistake is naming your estate as beneficiary of a retirement account, which triggers unnecessary income taxes and probate delays. Another is forgetting to update designations after major life events, marriage, divorce, or the birth of grandchildren. Proper wealth transfer planning requires reviewing every account with a beneficiary designation and ensuring it aligns with your overall legacy strategy.
Tax-Efficient Planning and Asset Protection
Taxes are often the largest expense in wealth transfer. Federal estate taxes, state inheritance taxes, and income taxes on inherited retirement accounts can consume 30-50% of an estate if not planned carefully. Tax-efficient legacy planning reduces this drain.
Common strategies include maximizing contributions to tax-advantaged retirement accounts, using trusts to manage taxable income across generations, timing charitable donations to create tax deductions, and structuring asset transfers to minimize capital gains taxes. The specifics depend entirely on your situation, your age, income, asset types, and state of residence all affect which strategies make sense.
Asset protection is the companion to tax efficiency. Trusts, proper titling of assets, and insurance strategies all play a role. For business owners, succession planning and buy-sell agreements protect your family's inheritance from business disputes.
Charitable Giving and Philanthropic Goals
If you care about causes beyond your family, charitable giving deserves a place in your legacy plan. Giving strategically can satisfy your philanthropic goals while creating meaningful tax benefits.
Donor-advised funds, charitable remainder trusts, and direct donations of appreciated assets all serve different purposes. A donor-advised fund lets you make a tax-deductible donation today but distribute grants to charities over many years. A charitable remainder trust pays you income during your lifetime, then distributes the remainder to charity, creating both income and charitable deductions.
The key is intentionality. A thoughtful charitable strategy ensures your money reaches causes you genuinely support while maximizing available tax benefits.
Charitable Giving Tax Benefits: Maximizing Your Impact
When you donate appreciated assets, stocks, real estate, or other property that has increased in value, you avoid capital gains tax on that appreciation and receive a charitable deduction for the full fair market value. This is far more efficient than selling the asset, paying capital gains tax, and donating the after-tax proceeds.
For high-income earners, bunching charitable donations in certain years can help you exceed the standard deduction threshold, allowing you to itemize and claim larger deductions. Donor-advised funds are particularly useful for this strategy.
If you have significant retirement account balances, a qualified charitable distribution allows you to donate directly from your IRA to charity after age 73, satisfying required minimum distributions while avoiding income tax on the distribution. This underutilized strategy can save substantial taxes for retirees who plan to give to charity anyway.
Building Your Legacy Planning Checklist
A legacy plan only works if it's complete and current.
Documents to Gather and Organize
Start by gathering all relevant financial and legal documents: bank statements, investment accounts, retirement account statements, property deeds, life insurance policies, business documents, and existing wills or trusts. Many people have accounts scattered across multiple institutions; consolidating this information is the first step.
Next, locate your legal documents: wills, trusts, powers of attorney, healthcare directives, and any prenuptial agreements. If you don't have these documents, creating them is a priority. If you have them but they're more than a few years old, review them, life changes and tax laws shift, and outdated documents can create problems.
Create a master inventory listing all accounts, policies, and documents with account numbers, login credentials stored securely, and contact information for relevant professionals. This inventory is invaluable to your family if something happens to you.
| Document Type | Status | Last Updated | Location |
|---|---|---|---|
| Will or Trust | Complete / Incomplete / Missing | [Date] | [Location] |
| Power of Attorney | Complete / Incomplete / Missing | [Date] | [Location] |
| Healthcare Directive | Complete / Incomplete / Missing | [Date] | [Location] |
| Beneficiary Designations | Reviewed / Not Reviewed | [Date] | [Account Info] |
| Property Deeds | Organized / Disorganized | [Date] | [Location] |
| Insurance Policies | Catalogued / Not Catalogued | [Date] | [Location] |
| Retirement Accounts | Listed / Not Listed | [Date] | [Account Info] |
| Investment Accounts | Listed / Not Listed | [Date] | [Account Info] |
Values-Based Planning and Family Communication
The documents are important, but values-based planning transforms a legacy plan from a legal exercise into a reflection of who you are. This requires honest conversations about what matters most: your family's financial security, education for grandchildren, charitable causes, business succession, or specific wishes for how your wealth should be used.
Many families avoid these conversations because money feels uncomfortable to discuss. Yet families that talk openly about values and expectations experience fewer conflicts after inheritance. Your adult children need to understand not just what they'll inherit, but why you made the decisions you did.
Consider writing a letter of intent that explains your values, your wishes, and your reasoning. This document, separate from your legal will, can be deeply personal and help your family understand your priorities.
How to Choose a Legacy Planning Advisor
Not all financial advisors are equipped to help with comprehensive legacy planning. The best legacy advisors combine deep technical knowledge with genuine interest in your family's long-term wellbeing.
Professional Credentials and Fiduciary Standards
Look for advisors who hold the Certified Financial Planner (CFP) designation, which requires rigorous training in comprehensive financial planning including estate and legacy planning. Other relevant credentials include Chartered Financial Consultant (ChFC) or Certified Estate Planner (CEP).
More importantly, verify that your advisor operates under a fiduciary standard. A fiduciary is legally obligated to act in your best interest, not their own. Ask directly: "Are you a fiduciary 100% of the time?" If an advisor hedges, that's a red flag.
Check the advisor's background through the Financial Industry Regulatory Authority (FINRA) BrokerCheck database and the SEC's Investment Adviser Public Disclosure system. Experience matters, an advisor who has guided dozens of families through legacy planning and wealth transfer has encountered situations you haven't and can anticipate problems.
Evaluating Cost, Services, and Fit
Fee structure varies significantly. Some advisors charge a percentage of assets under management (AUM), others charge flat fees, and some work on a fee-only basis. Each model has trade-offs.
Beyond fees, evaluate the scope of services. Does the advisor offer comprehensive planning or just investment management? Can they help with Medicare navigation, Social Security strategy, insurance review, and tax planning?
Assess whether the advisor listens and asks good questions. A strong legacy planning conversation includes questions about your values, your family situation, your concerns, and your vision for your family's future. If an advisor jumps straight to investment recommendations without understanding your full situation, that's a problem.
Finally, consider personality fit. You'll be working with this person during important financial decisions. You need to trust them and feel comfortable asking questions.
Why Professional Financial Legacy Planning Matters
You might be tempted to handle legacy planning yourself using online tools or software. There are legitimate reasons to consider professional guidance instead.
First, complexity compounds. A simple estate might be manageable DIY, but if you have multiple properties, retirement accounts, investment accounts, life insurance, a business, or a blended family, the interactions between different pieces become intricate. A mistake in one area can ripple through others.
Second, tax savings from professional planning often exceed the cost of the advice. A well-structured legacy plan can save tens of thousands or hundreds of thousands in taxes over your lifetime and your family's inheritance.
Third, professional advisors bring objectivity and accountability. They've guided many families through similar situations and can anticipate problems. They also hold you accountable to your plan.
Finally, professional guidance provides peace of mind. When you know your plan is complete, legally sound, tax-efficient, and aligned with your values, you can stop worrying and start enjoying your retirement.
Getting Started with Your Legacy Plan Today
If you've been putting off legacy planning, the best time to start is now.
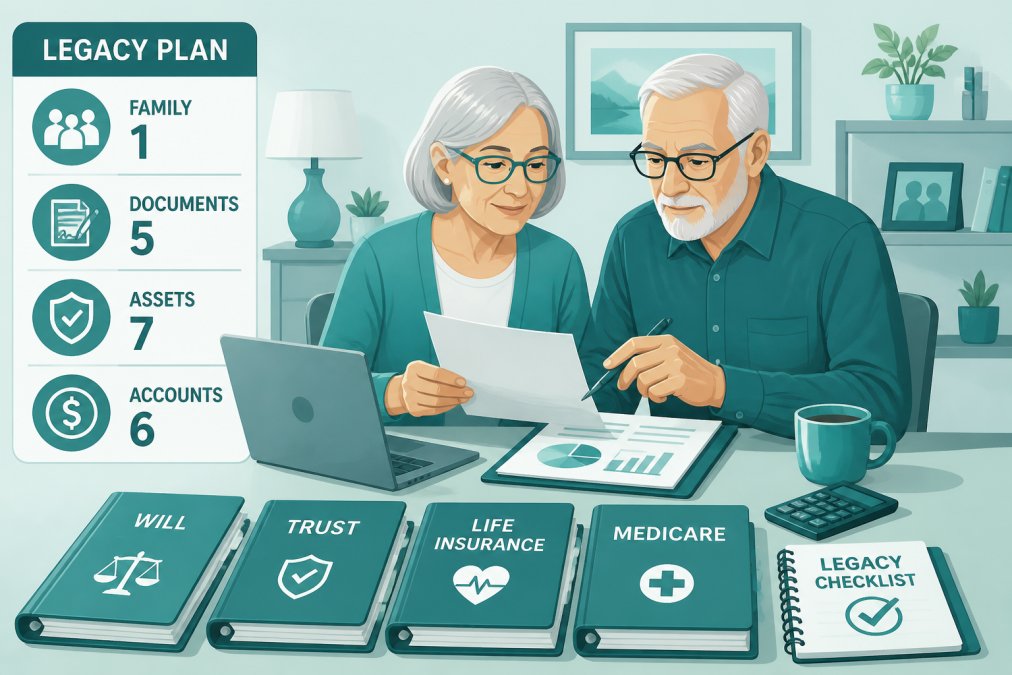
Start with a financial inventory. Gather statements from all your accounts, list your assets, and document any debts. You don't need perfect information, a rough inventory is enough to begin.
Next, identify your priorities. What matters most? Family security? Charitable giving? Business succession? Minimizing taxes? Your priorities will shape every other decision in your plan.
Then, address the foundational documents. If you don't have a will, trust, power of attorney, and healthcare directive, creating these should be your first priority.
Once documents are in place, review your beneficiary designations. Make sure every account with a beneficiary designation is aligned with your overall plan.
Finally, consider professional guidance. If your situation is straightforward, you might handle planning yourself. If you have significant assets, a complex family situation, or business interests, professional advice is worth the investment. New Insight Financial specializes in helping individuals and couples organize their financial lives for retirement and legacy. Our team can help you develop a comprehensive strategy that addresses income planning, tax efficiency, family protection, and your long-term vision.
The Generational Vault® secure online storage makes it easy to organize all your documents in one accessible place. Your family can access critical information anytime, anywhere, whether you need to reference something today or they need it in an emergency.
Frequently Asked Questions
What is the difference between estate planning and financial legacy planning?
Estate planning focuses on creating legal documents like wills and trusts to direct asset distribution after death and minimize probate. Financial legacy planning is broader, it combines estate planning with retirement income strategies, tax-efficient wealth transfer, investment management, and values-based financial decisions that reflect your life goals. Financial legacy planning also addresses how to prepare beneficiaries for wealth transfer and ensures your financial decisions align with your family's long-term vision.
At what age should you start financial legacy planning?
Most financial advisors recommend starting in your 50s, especially if you're transitioning toward retirement. However, the right time depends on your circumstances. If you have significant assets, a family, or complex financial situations, starting earlier helps you build a more comprehensive strategy. Even if you're a few years from retirement, professional guidance ensures your income projections account for healthcare costs, market volatility, and long-term care needs, not just optimistic paper numbers.
What services do financial legacy planning advisors actually provide?
Comprehensive financial legacy planning services include retirement income planning, tax-efficient withdrawal strategies, investment management, Medicare and Social Security guidance, beneficiary designation reviews, trust implementation, charitable giving strategies, and document organization. Many advisors also help families communicate values across generations and protect against major retirement risks like market downturns or unexpected healthcare expenses. Services vary by advisor, so clarify what's included before committing.
How do I know if a financial advisor's retirement projections are realistic?
Ask how the advisor accounts for real-world factors: healthcare inflation, market downturns during withdrawal years, sequence-of-returns risk, and Social Security timing. Realistic projections use conservative assumptions, run multiple scenarios (best case, worst case, likely case), and stress-test against historical market data. Be skeptical of projections that show only one optimistic outcome or don't address what happens if markets decline early in retirement. A good advisor explains their methodology and updates projections annually as circumstances change.
Legacy planning is not a one-time event. It's an evolving process that should be reviewed annually and adjusted when major life changes occur. Start now, even if your plan isn't perfect. A good plan that exists beats a perfect plan that never gets created. Your family's security and your lasting impact depend on it.
Get started with New Insight Financial and create a legacy plan that reflects your values, protects your family, and ensures your wealth serves your vision for generations to come.