 how-to
Calculate Social Security Break-Even Age: A Step-by-Step Guide
Table of Contents
- What Is the Social Security Break-Even Age?
- Step-by-Step: How to Calculate Social Security Break-Even Age
- Social Security Full Retirement Age Chart and How It Shapes Your Break-Even Point
- How Social Security Delayed Retirement Credits Shift the Math
- The Impact of Early Claiming on Social Security Benefits and Your Break-Even Age
- Why the Break-Even Age Is Not the Only Number That Matters
- Common Mistakes to Avoid When Running Your Break-Even Calculation
- Conclusion: Use Your Break-Even Age as Part of a Broader Retirement Income Strategy
- Frequently Asked Questions
Last Updated: September 7, 2026
What Is the Social Security Break-Even Age?
The Social Security break-even age is the point in retirement when the cumulative benefits you receive from claiming early equal what you would have received by waiting for a higher monthly payment. In simple terms, it is the age at which delaying your claim starts to pay off financially. This calculation matters because it helps you decide between taking a reduced benefit at age 62 or waiting to collect a larger monthly amount later.
Most retirees face this decision without a clear framework. The break-even analysis provides one, turning an emotional choice into a numbers-driven one. The break-even analysis provides one, turning an emotional choice into a numbers-driven one.
The core tension is simple: claim early and you receive more checks, but each check is smaller. Wait, and you receive fewer checks, but each one is larger and includes valuable Social Security Administration guidance on delayed retirement credits. The break-even age reveals which path delivers more total dollars over your lifetime.
Step-by-Step: How to Calculate Social Security Break-Even Age
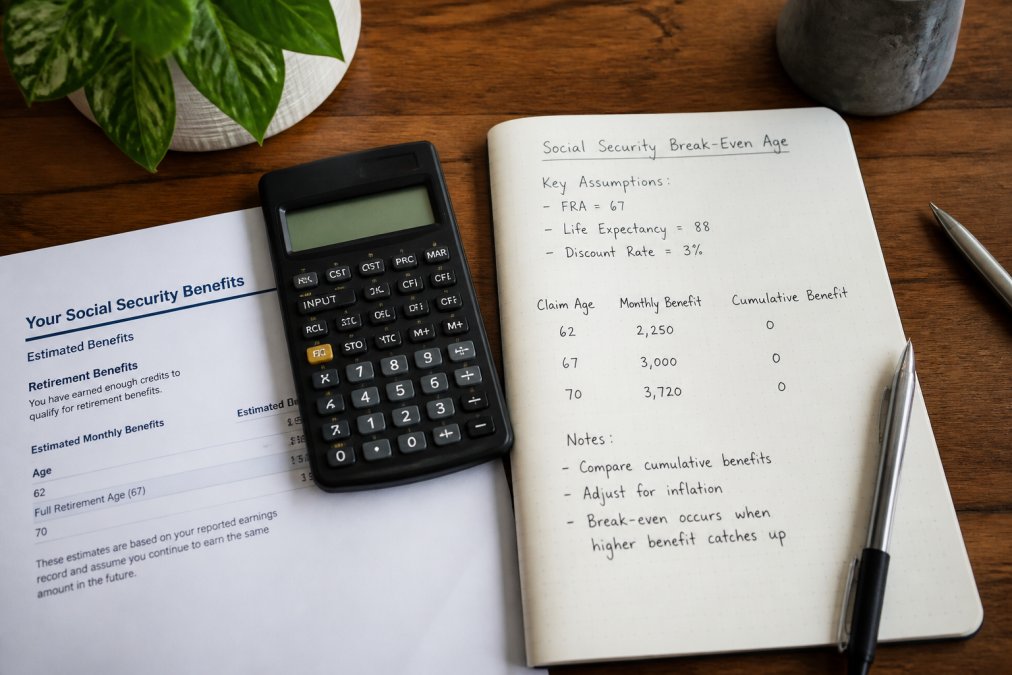
Calculating your break-even age requires three pieces of information: your full retirement age, your estimated monthly benefits at different claiming ages, and a simple cumulative comparison. You can complete the math by hand in about ten minutes using your Social Security statement from the SSA, which shows your benefit estimates at age 62, full retirement age, and age 70.
Step 1: Find Your Full Retirement Age
Your full retirement age, often abbreviated as FRA, is determined by your birth year. For anyone born in 1960 or later, full retirement age is 67. If you were born between 1943 and 1954, it is 66, with incremental increases for birth years in between. The Social Security Administration's full retirement age chart provides the exact age for your situation. This number serves as your baseline because benefits claimed at FRA equal your full primary insurance amount.
Step 2: Determine Your Monthly Benefit Amounts
Your Social Security statement lists your estimated monthly benefit at three key claiming ages: 62, your full retirement age, and 70. These figures already account for early filing penalties and delayed retirement credits. If you claim at 62, your benefit is permanently reduced by 25 percent if your FRA is 66, or 30 percent if your FRA is 67. If you wait until 70, you earn delayed retirement credits of 8 percent per year for each year past FRA. Write down all three numbers before moving to the next step.
Step 3: Calculate Cumulative Lifetime Benefits
The break-even formula compares total dollars received under each scenario. Start with the annual benefit for claiming at 62, multiply it by the number of years you expect to collect, and do the same for claiming at FRA or 70. The break-even age is where the cumulative totals intersect.
A practical example clarifies the math. Suppose your full retirement age benefit is $1,500 per month. Claiming at 62 reduces that to roughly $1,050 per month. Claiming at 70 increases it to about $1,860 per month. For the first eight years, the early claimant collects more total dollars. But around age 78 to 80, the person who waited begins to pull ahead.
| Claiming Age | Monthly Benefit | Annual Total | Break-Even Approx. |
|---|---|---|---|
| 62 | $1,050 | $12,600 | Starts ahead |
| 67 (FRA) | $1,500 | $18,000 | Catches up ~age 78 |
| 70 | $1,860 | $22,320 | Pulls ahead ~age 80 |
Step 4: Refine the Calculation with a More Precise Formula
While the simple cumulative comparison above gives you a solid estimate, a more precise calculation accounts for the fact that you receive monthly, not annual, payments. For a comparison between claiming at 62 and claiming at FRA, the formula is:
Break-Even Age = Claiming Age (Early) + (Early Monthly Benefit × Months Received) ÷ (FRA Monthly Benefit - Early Monthly Benefit)
Using the example above, if you claim at 62 with a $1,050 monthly benefit and your FRA benefit is $1,500, the monthly difference is $450. The cumulative advantage of claiming early after 60 months (five years) is $63,000. Dividing that by the $450 monthly difference gives you 140 months, or about 11.7 years. Adding that to age 62 puts your break-even at roughly age 73.7, slightly earlier than the simple annual estimate because it accounts for the monthly timing of payments.
Step 5: Run the Same Comparison for Age 70
To compare claiming at 62 versus age 70, use the same formula. With a $1,860 monthly benefit at 70, the difference from the age-62 benefit is $810 per month. By age 70, the early claimant has received 96 months of payments, totaling $100,800. Dividing that by the $810 monthly difference gives you about 124 months, or roughly 10.3 years. Adding that to age 70 puts the break-even at approximately age 80.3.
This more precise method reveals that your break-even age shifts depending on which two claiming ages you compare. Running all three comparisons gives you a complete picture of how the trade-offs change across your claiming options.
Social Security Full Retirement Age Chart and How It Shapes Your Break-Even Point
Your full retirement age directly determines how large the gap is between early and delayed claiming, which shifts your break-even point. A later FRA means a larger reduction for claiming at 62, pushing your break-even age further out.
The chart below shows the exact FRA based on your birth year, along with the corresponding reduction for claiming at 62 and the increase for waiting until 70.
| Birth Year | Full Retirement Age | Reduction at 62 | Increase at 70 |
|---|---|---|---|
| 1943-1954 | 66 | 25.0% | 32.0% |
| 1955 | 66 and 2 months | 25.8% | 30.7% |
| 1956 | 66 and 4 months | 26.7% | 29.3% |
| 1957 | 66 and 6 months | 27.5% | 28.0% |
| 1958 | 66 and 8 months | 28.3% | 26.7% |
| 1959 | 66 and 10 months | 29.2% | 25.3% |
| 1960 or later | 67 | 30.0% | 24.0% |
For someone with an FRA of 67, claiming at 62 results in a 30 percent reduction in monthly benefits. That permanent cut is substantial.
The incremental FRA increases for those born between 1955 and 1959 create a more complex decision. Someone born in 1955 has an FRA of 66 and 2 months, which means their reduction for claiming at 62 is 25.8 percent, slightly less than someone born in 1960. This difference, while seemingly small, shifts the break-even age by several months.
The delayed retirement credit structure also varies by birth year. For those with an FRA of 66, the credit is 8 percent per year, applied monthly, which compounds to a 32 percent increase by age 70. For those with an FRA of 67, the same 8 percent annual credit applies, but it only accumulates for three years instead of four, resulting in a 24 percent total increase by age 70.
A practical example illustrates how FRA shifts the math. Consider two workers with the same $2,000 monthly benefit at their respective FRAs. Worker A was born in 1954 with an FRA of 66. Claiming at 62 gives them $1,500 per month, while waiting until 70 gives them $2,640 per month. Worker B was born in 1960 with an FRA of 67. Claiming at 62 gives them $1,400 per month, while waiting until 70 gives them $2,480 per month.
Understanding this chart matters because it prevents you from relying on generic advice like "wait until 70" or "claim at 62." The optimal strategy depends on your specific FRA, which is locked in by your birth year.
How Social Security Delayed Retirement Credits Shift the Math
Delayed retirement credits are the financial incentive Social Security offers for waiting past your full retirement age. For each year you delay between FRA and age 70, your benefit grows by a fixed percentage, and this growth makes the break-even calculation more favorable to waiting. The credits stop accumulating at age 70.
A benefit claimed at 70 can be roughly 24 to 32 percent higher than the same benefit claimed at FRA, depending on your birth year.
The Impact of Early Claiming on Social Security Benefits and Your Break-Even Age
Claiming Social Security at 62 carries a permanent reduction that follows you for life, and understanding the impact of early claiming on Social Security benefits is essential before you make the decision. The reduction is not a temporary penalty; it becomes your benefit base for every future cost of living adjustment.
Early claiming also affects spousal and survivor benefits. If you claim early, your spouse's survivor benefit may be permanently reduced if it is based on your record. A surviving spouse often needs the higher benefit more than the couple needed the early income.
Why the Break-Even Age Is Not the Only Number That Matters
The break-even age answers one question, but it does not answer every question. Your claiming decision should also account for taxes, spousal coordination, and your total retirement picture.
Tax Implications of Social Security Benefits
Social Security benefits can be subject to federal income tax depending on your combined income. Up to 85 percent of your benefits may be taxable if your provisional income exceeds certain thresholds. Running the calculation on a pre-tax basis can overstate the advantage of one claiming strategy over another.
Spousal Benefit Considerations
For married couples, the claiming decision is rarely an individual one. A lower-earning spouse may claim a spousal benefit based on the higher earner's record, and the higher earner's decision to delay can substantially increase the survivor benefit. Couples who delay the higher earner's claim often secure a larger lifetime benefit for the surviving spouse.
Common Mistakes to Avoid When Running Your Break-Even Calculation
Most people make the same handful of errors when they run this calculation, and each one can skew the result. The most common mistake is treating the break-even point as a fixed age rather than a range that depends on your assumptions.
Another frequent error is ignoring the time value of money. A dollar collected at 62 is worth more today than a dollar collected at 75, simply because it can be invested. Finally, many retirees forget to factor in their own health and family longevity. The Social Security Administration publishes actuarial life tables, but your personal health history may argue for claiming earlier than the average suggests.
Conclusion: Use Your Break-Even Age as Part of a Broader Retirement Income Strategy
The break-even age gives you a clear financial lens on when to claim Social Security, but it works best as one input in a complete retirement income strategy. Your decision should also account for your savings withdrawal plan, pension integration, healthcare costs, and the security you want to leave for a spouse.
At New Insight Financial, we help clients build retirement income plans that weigh the break-even analysis alongside their full financial picture, including Medicare navigation and protection against the major risks that can derail retirement. Our personalized approach considers your risk tolerance, your family situation, and your long-term goals. If you are approaching this decision and want a second set of eyes on the math, contact New Insight Financial to discuss your claiming strategy and get started today.
Frequently Asked Questions
What is the formula for calculating Social Security break-even age?
To find your break-even age, subtract your lower monthly benefit from your higher monthly benefit to get the monthly difference. Then divide the total amount you would forgo by waiting (the higher benefit multiplied by the number of months you delay) by that monthly difference. The result is the number of months you must live past your full retirement age to come out ahead by waiting.
Does the Social Security break-even age account for cost-of-living adjustments?
A simple break-even calculation does not include cost-of-living adjustments (COLAs). Since COLAs apply to both early and delayed benefits, the basic comparison remains roughly accurate. However, because a delayed benefit starts from a higher base amount, the same percentage COLA produces a larger dollar increase each year. This can make your actual break-even age arrive slightly earlier than a nominal calculation suggests.
How does life expectancy impact the decision to delay Social Security benefits?
Your personal life expectancy is the single most important factor in this decision. If you expect to live past your break-even age, delaying benefits gives you more cumulative lifetime income. If your health is poor or family history suggests a shorter lifespan, claiming earlier may be the better financial move. Break-even analysis is a planning tool, not a guarantee of the right answer.
How do I use the Social Security Administration's online calculators to estimate my break-even point?
Start by creating a my Social Security account at the Social Security Administration's website to view your official earning history and benefit estimates at different filing ages. Use the detailed calculator to adjust for future earnings if you are still working. Compare the monthly benefit amounts shown for age 62, your full retirement age, and age 70, then apply those figures to the break-even formula.